
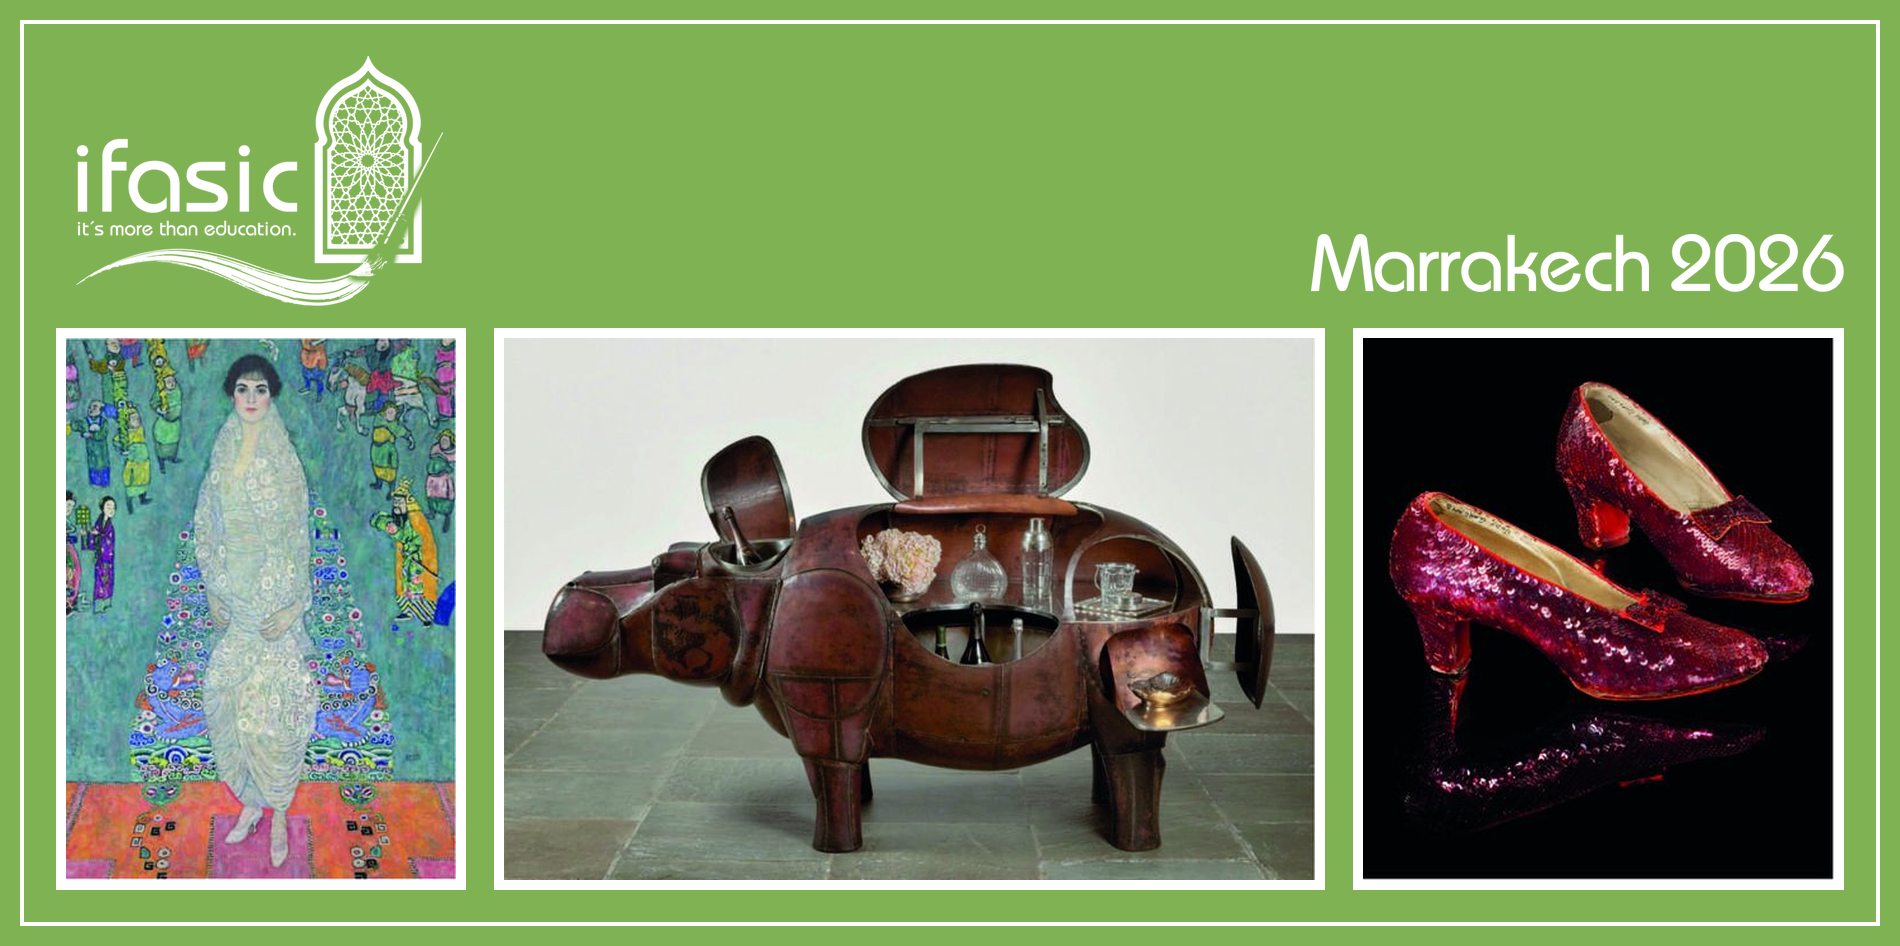
Appraisers, adjusters, underwriters, and brokers alike know the potential perils of infrequent attention to scheduled values for fine and decorative arts and collectibles, and yet, in a soft insurance market, there may be temptation on the part of carriers to waive the reappraisal clause for fear of losing accounts. AI products combing schedules to advise on reappraisal needs may only exacerbate the issue, giving false illusions of security.
Failure to reappraise collections on a timely basis may initially seem mostly to be an insured’s problem, and in rising markets, this may be largely true. A procession of eye-watering auction results in the fine art markets make regular headlines. Last November at Sotheby’s, New York, Gustav Klimt’s Portrait of Elisabeth Lederer sold for $236.4M, the highest auction price ever realized for a work of modern art, and the highest realized for any lot in that auction house’s 282-year history. In May, nine-figure records were set for Jackson Pollock and Constantin Brancusi at Christie’s, with an auction record set for Mark Rothko just shy of that level at $98.4M. In light of these sales, collectors of modern art, not limited to these artists, would be wise to investigate whether their schedules are now outdated. Since the high end of the art market is largely supply driven, often with few direct analogous sales, these data points could serve as relevant comparables for the valuation of similarly rare and important works by a range of artists.
Certain art market sectors have recently opened widely, with swiftly growing prices realized for notable works by Surrealists, historically undervalued female artists, and South Asian artists. Adjacent to fine art, pronounced growth can be seen in the market for important Design, emblematized by a craze for the whimsical creations of husband-and-wife makers François-Xavier and Claude Lalanne. A Lalanne hippopotamus bar fetched $31.4M at Sotheby’s last December, over quadruple the auction high for either Lalanne five years ago.
The frothy fine art markets have increasingly been joined by spiraling markets for collectibles, energized by newly monied buyers whose priorities lie largely outside fine art; other collectors are increasingly taking a cross-sector approach, looking for best in class, spanning the markets for fine art and collectibles. In the past three years, numerous auction records have been shattered for high-end non-art property such as electric vehicles ($40M), entertainment memorabilia ($32.5M), fossilized dinosaur skeletons ($50.1M), handbags ($10.1M), sports memorabilia ($24.1M), and trading cards ($16.5M).
If an insured has a pair of Dorothy’s ruby slippers scheduled for $2 million, i.e., in line with a 2012 price paid for another pair, and the policy allows partial loss to be calculated against 150% of scheduled value, that figure would be $3 million, which is less than 10% of the price paid for another such pair at Heritage Auctions in 2024. Reappraising every three to five years may be a basic rule of thumb for many items (and in some markets, it works), but in rapidly upwardly mobile markets, following such conventional wisdom may leave a collector dramatically underinsured and highly exposed to underpayment in the event of a loss.
The smartest strategy is often to monitor the market (or have one’s advisors do so), and to commission reappraisals following benchmark comparable sales, lest collectors find themselves highly underinsured. Indeed, such situations are hardly just hypothetical. I recently appraised partial loss in value for a contemporary painting, which, as of the date of loss, I valued at $630,000 (Retail Replacement Value), about 3.6 times higher than its scheduled value of $173,000 and about 2.4 times higher than the item limit with the policy’s 150% allowance.
There are even markets in which collectors should consider commissioning appraisals immediately after purchase, such as when paying preferential prices. When selling new works from the studio in the “primary market,” galleries lock in prices with their artists. When an artist is popular, and demand exceeds supply, galleries must find ways to allocate works of art, variously granting coveted primary-market access to high-profile collectors, those with institutional affiliations, and those who have extensively supported the gallery’s program. Other prospective collectors may be put on a “waiting list,” though in reality, there is often no front of the queue. In such situations, prospective buyers who have been disallowed to buy in the primary market must compete at auction where prices can be multiples higher. Moreover, secondary-market dealers often mirror auction prices -- and that frequently includes the very gallery that represents the artist selling secondary works for double or triple.
Whereas scheduling most works of art with a purchase receipt makes perfect sense, this is not the case for such popular artists. A collector fortunate enough to have been granted access to buy in the primary market for, let’s say, $100,000 may consider immediately seeking appraisal for insurance scheduling purposes, if for no other reason, because repeat primary access cannot be guaranteed. A total-loss payout of $100,000 against such a scheduled value would potentially leave the insured unable to replace the property, given the scarcity of available works at such prices; the only buying opportunities may be in the secondary market for triple such a level. In short, the $100,000 retail price paid may not be the Retail Replacement Value of the work at the time. An appraiser would need to examine the auction market and the secondary retail market to identify the appropriate comparable sales and offerings that would demonstrate the amount that would actually be needed to replace the property in a timely manner.
While, for works by artists with rapidly growing markets, enforcement of the reappraisal clause promotes proper protection for insureds and ensures that appropriately rising premiums are paid to carriers, conversely, in declining markets, enforcement of the reappraisal clause can provide much-needed protection for the carrier, lest they be responsible for grossly excessive payments for claims for overvalued works of art. Moreover, insureds need not pay premium on value that simply is not there.
This scenario is perhaps most readily visible in the markets for emerging art. Since covid, volatility in these markets has been even more extreme than normally high levels (relative to other art market sectors). Speculation on emerging artists, many young and with little or no institutional backing, was rampant in and around 2020- 22. Simultaneous softening of both stock and bond markets further fueled an already growing interest in using emerging art as a potentially high-yield investment vehicle -- and indeed, some flippers made millions in secondary-market sales at auction or otherwise for artists with scarce primary-market supply. However, once market fever subsides for an artist (as it frequently does, particularly for those with slim institutional backing), and there is no longer a waiting list, auction will generally yield a fraction of the high prices -- and often much less than the original primary-market prices.
In the markets for some emerging artists, auction prices (and by extension, values), dropped by more than 90% between 2021-22 and 2024-25. Collectors may have had such works insured at the height of the market, whether scheduled values were based on purchase receipts or appraisals. If a work by such an artist were to have been valued for insurance scheduling purposes in 2022 and the schedule were to remain untouched, in the event of a claim today, the carrier could be responsible for outsized payouts, possibly severalfold (in extreme cases, 20-fold!) above an appropriate level.
Overvaluation with risk to carriers is also apparent in more developed art markets, which may experience more incremental downward drift. The markets for some major contemporary artists such as Damien Hirst, Sterling Ruby, Rudolf Stingel, and Christopher Wool are broadly softer than they were a decade or so ago. While the percentages of price contraction for works by such artists are generally not nearly as precipitous as they are for those emerging artists, in absolute terms of dollars and pounds, the potential ramifications that may result from infrequent reappraisal of overvalued works by such major artists may be even greater, leaving carriers exposed to highly excessive payouts in the event of losses.
Following 2023-25, a period of muted overall sales figures, today’s art market has characteristics of a K-shaped economy; record prices are routinely realized for significant works by in-demand blue-chip artists, while retrenchment persists in other market segments. The rapidity of changes in the art market, including the progression through full market cycles in just a few years, should matter to the insurance market. As a growing set of environmental risks dovetails with increasingly volatile markets, we should expect potential for significant claims for works of art with outdated scheduled values. Both underwriters and insureds are best served by timely reappraisal to ensure that schedules are maximally in step with present market realities.