
Join me live for the next episode of Risk Thinkers, “The Art of Recovery: Navigating Fine Art Claims,” on November 10th at 2pm. I will be speaking about the complexities of partial-loss art claims, along with Margaret Schmitz of PURE Insurance and Delia Müller-Wüsten of New York Art Conservation. The panel discussion will be followed by a live Q&A and an update on PURE from President Dave Logan. Please message PURE for registration information.
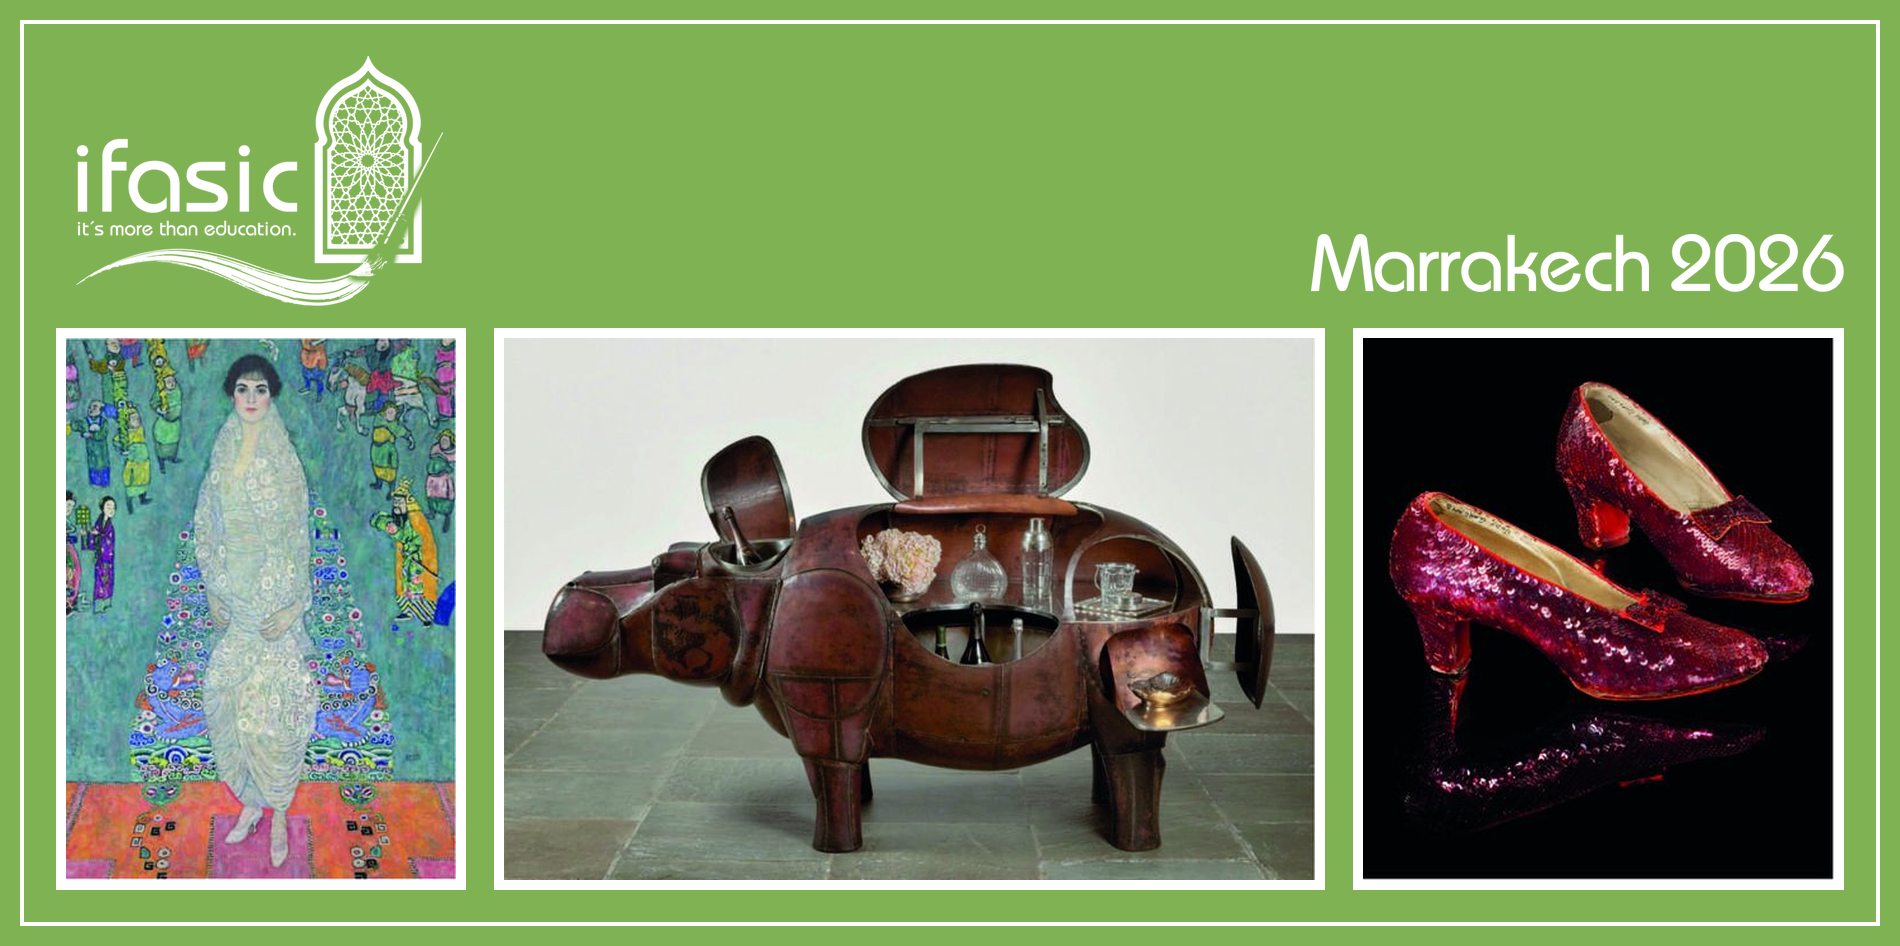
(l. to r.) Gustav Klimt, Portrait of Elisabeth Lederer, 1914-16, oil on canvas, 71 x 51.4 inches; François-Xavier Lalanne, Hippopotame Bar; Ruby Slippers from The Wizard of Oz, 1939
Reappraisal of art in a volatile market (IFASIC conference program article)
Appraisers, adjusters, underwriters, and brokers alike know the potential perils of infrequent attention to scheduled values for fine and decorative arts and collectibles, and yet, in a soft insurance market, there may be temptation on the part of carriers to waive the reappraisal clause for fear of losing accounts. AI products combing schedules to advise on reappraisal needs may only exacerbate the issue, giving false illusions of security.
Failure to reappraise collections on a timely basis may initially seem mostly to be an insured’s problem, and in rising markets, this may be largely true. A procession of eye-watering auction results in the fine art markets make regular headlines. Last November at Sotheby’s, New York, Gustav Klimt’s Portrait of Elisabeth Lederer sold for $236.4M, the highest auction price ever realized for a work of modern art, and the highest realized for any lot in that auction house’s 282-year history. In May, nine-figure records were set for Jackson Pollock and Constantin Brancusi at Christie’s, with an auction record set for Mark Rothko just shy of that level at $98.4M. In light of these sales, collectors of modern art, not limited to these artists, would be wise to investigate whether their schedules are now outdated. Since the high end of the art market is largely supply driven, often with few direct analogous sales, these data points could serve as relevant comparables for the valuation of similarly rare and important works by a range of artists.
Certain art market sectors have recently opened widely, with swiftly growing prices realized for notable works by Surrealists, historically undervalued female artists, and South Asian artists. Adjacent to fine art, pronounced growth can be seen in the market for important Design, emblematized by a craze for the whimsical creations of husband-and-wife makers François-Xavier and Claude Lalanne. A Lalanne hippopotamus bar fetched $31.4M at Sotheby’s last December, over quadruple the auction high for either Lalanne five years ago.
The frothy fine art markets have increasingly been joined by spiraling markets for collectibles, energized by newly monied buyers whose priorities lie largely outside fine art; other collectors are increasingly taking a cross-sector approach, looking for best in class, spanning the markets for fine art and collectibles. In the past three years, numerous auction records have been shattered for high-end non-art property such as electric vehicles ($40M), entertainment memorabilia ($32.5M), fossilized dinosaur skeletons ($50.1M), handbags ($10.1M), sports memorabilia ($24.1M), and trading cards ($16.5M).
If an insured has a pair of Dorothy’s ruby slippers scheduled for $2 million, i.e., in line with a 2012 price paid for another pair, and the policy allows partial loss to be calculated against 150% of scheduled value, that figure would be $3 million, which is less than 10% of the price paid for another such pair at Heritage Auctions in 2024. Reappraising every three to five years may be a basic rule of thumb for many items (and in some markets, it works), but in rapidly upwardly mobile markets, following such conventional wisdom may leave a collector dramatically underinsured and highly exposed to underpayment in the event of a loss.
The smartest strategy is often to monitor the market (or have one’s advisors do so), and to commission reappraisals following benchmark comparable sales, lest collectors find themselves highly underinsured. Indeed, such situations are hardly just hypothetical. I recently appraised partial loss in value for a contemporary painting, which, as of the date of loss, I valued at $630,000 (Retail Replacement Value), about 3.6 times higher than its scheduled value of $173,000 and about 2.4 times higher than the item limit with the policy’s 150% allowance.
There are even markets in which collectors should consider commissioning appraisals immediately after purchase, such as when paying preferential prices. When selling new works from the studio in the “primary market,” galleries lock in prices with their artists. When an artist is popular, and demand exceeds supply, galleries must find ways to allocate works of art, variously granting coveted primary-market access to high-profile collectors, those with institutional affiliations, and those who have extensively supported the gallery’s program. Other prospective collectors may be put on a “waiting list,” though in reality, there is often no front of the queue. In such situations, prospective buyers who have been disallowed to buy in the primary market must compete at auction where prices can be multiples higher. Moreover, secondary-market dealers often mirror auction prices -- and that frequently includes the very gallery that represents the artist selling secondary works for double or triple.
Whereas scheduling most works of art with a purchase receipt makes perfect sense, this is not the case for such popular artists. A collector fortunate enough to have been granted access to buy in the primary market for, let’s say, $100,000 may consider immediately seeking appraisal for insurance scheduling purposes, if for no other reason, because repeat primary access cannot be guaranteed. A total-loss payout of $100,000 against such a scheduled value would potentially leave the insured unable to replace the property, given the scarcity of available works at such prices; the only buying opportunities may be in the secondary market for triple such a level. In short, the $100,000 retail price paid may not be the Retail Replacement Value of the work at the time. An appraiser would need to examine the auction market and the secondary retail market to identify the appropriate comparable sales and offerings that would demonstrate the amount that would actually be needed to replace the property in a timely manner.
While, for works by artists with rapidly growing markets, enforcement of the reappraisal clause promotes proper protection for insureds and ensures that appropriately rising premiums are paid to carriers, conversely, in declining markets, enforcement of the reappraisal clause can provide much-needed protection for the carrier, lest they be responsible for grossly excessive payments for claims for overvalued works of art. Moreover, insureds need not pay premium on value that simply is not there.
This scenario is perhaps most readily visible in the markets for emerging art. Since covid, volatility in these markets has been even more extreme than normally high levels (relative to other art market sectors). Speculation on emerging artists, many young and with little or no institutional backing, was rampant in and around 2020- 22. Simultaneous softening of both stock and bond markets further fueled an already growing interest in using emerging art as a potentially high-yield investment vehicle -- and indeed, some flippers made millions in secondary-market sales at auction or otherwise for artists with scarce primary-market supply. However, once market fever subsides for an artist (as it frequently does, particularly for those with slim institutional backing), and there is no longer a waiting list, auction will generally yield a fraction of the high prices -- and often much less than the original primary-market prices.
In the markets for some emerging artists, auction prices (and by extension, values), dropped by more than 90% between 2021-22 and 2024-25. Collectors may have had such works insured at the height of the market, whether scheduled values were based on purchase receipts or appraisals. If a work by such an artist were to have been valued for insurance scheduling purposes in 2022 and the schedule were to remain untouched, in the event of a claim today, the carrier could be responsible for outsized payouts, possibly severalfold (in extreme cases, 20-fold!) above an appropriate level.
Overvaluation with risk to carriers is also apparent in more developed art markets, which may experience more incremental downward drift. The markets for some major contemporary artists such as Damien Hirst, Sterling Ruby, Rudolf Stingel, and Christopher Wool are broadly softer than they were a decade or so ago. While the percentages of price contraction for works by such artists are generally not nearly as precipitous as they are for those emerging artists, in absolute terms of dollars and pounds, the potential ramifications that may result from infrequent reappraisal of overvalued works by such major artists may be even greater, leaving carriers exposed to highly excessive payouts in the event of losses.
Following 2023-25, a period of muted overall sales figures, today’s art market has characteristics of a K-shaped economy; record prices are routinely realized for significant works by in-demand blue-chip artists, while retrenchment persists in other market segments. The rapidity of changes in the art market, including the progression through full market cycles in just a few years, should matter to the insurance market. As a growing set of environmental risks dovetails with increasingly volatile markets, we should expect potential for significant claims for works of art with outdated scheduled values. Both underwriters and insureds are best served by timely reappraisal to ensure that schedules are maximally in step with present market realities.
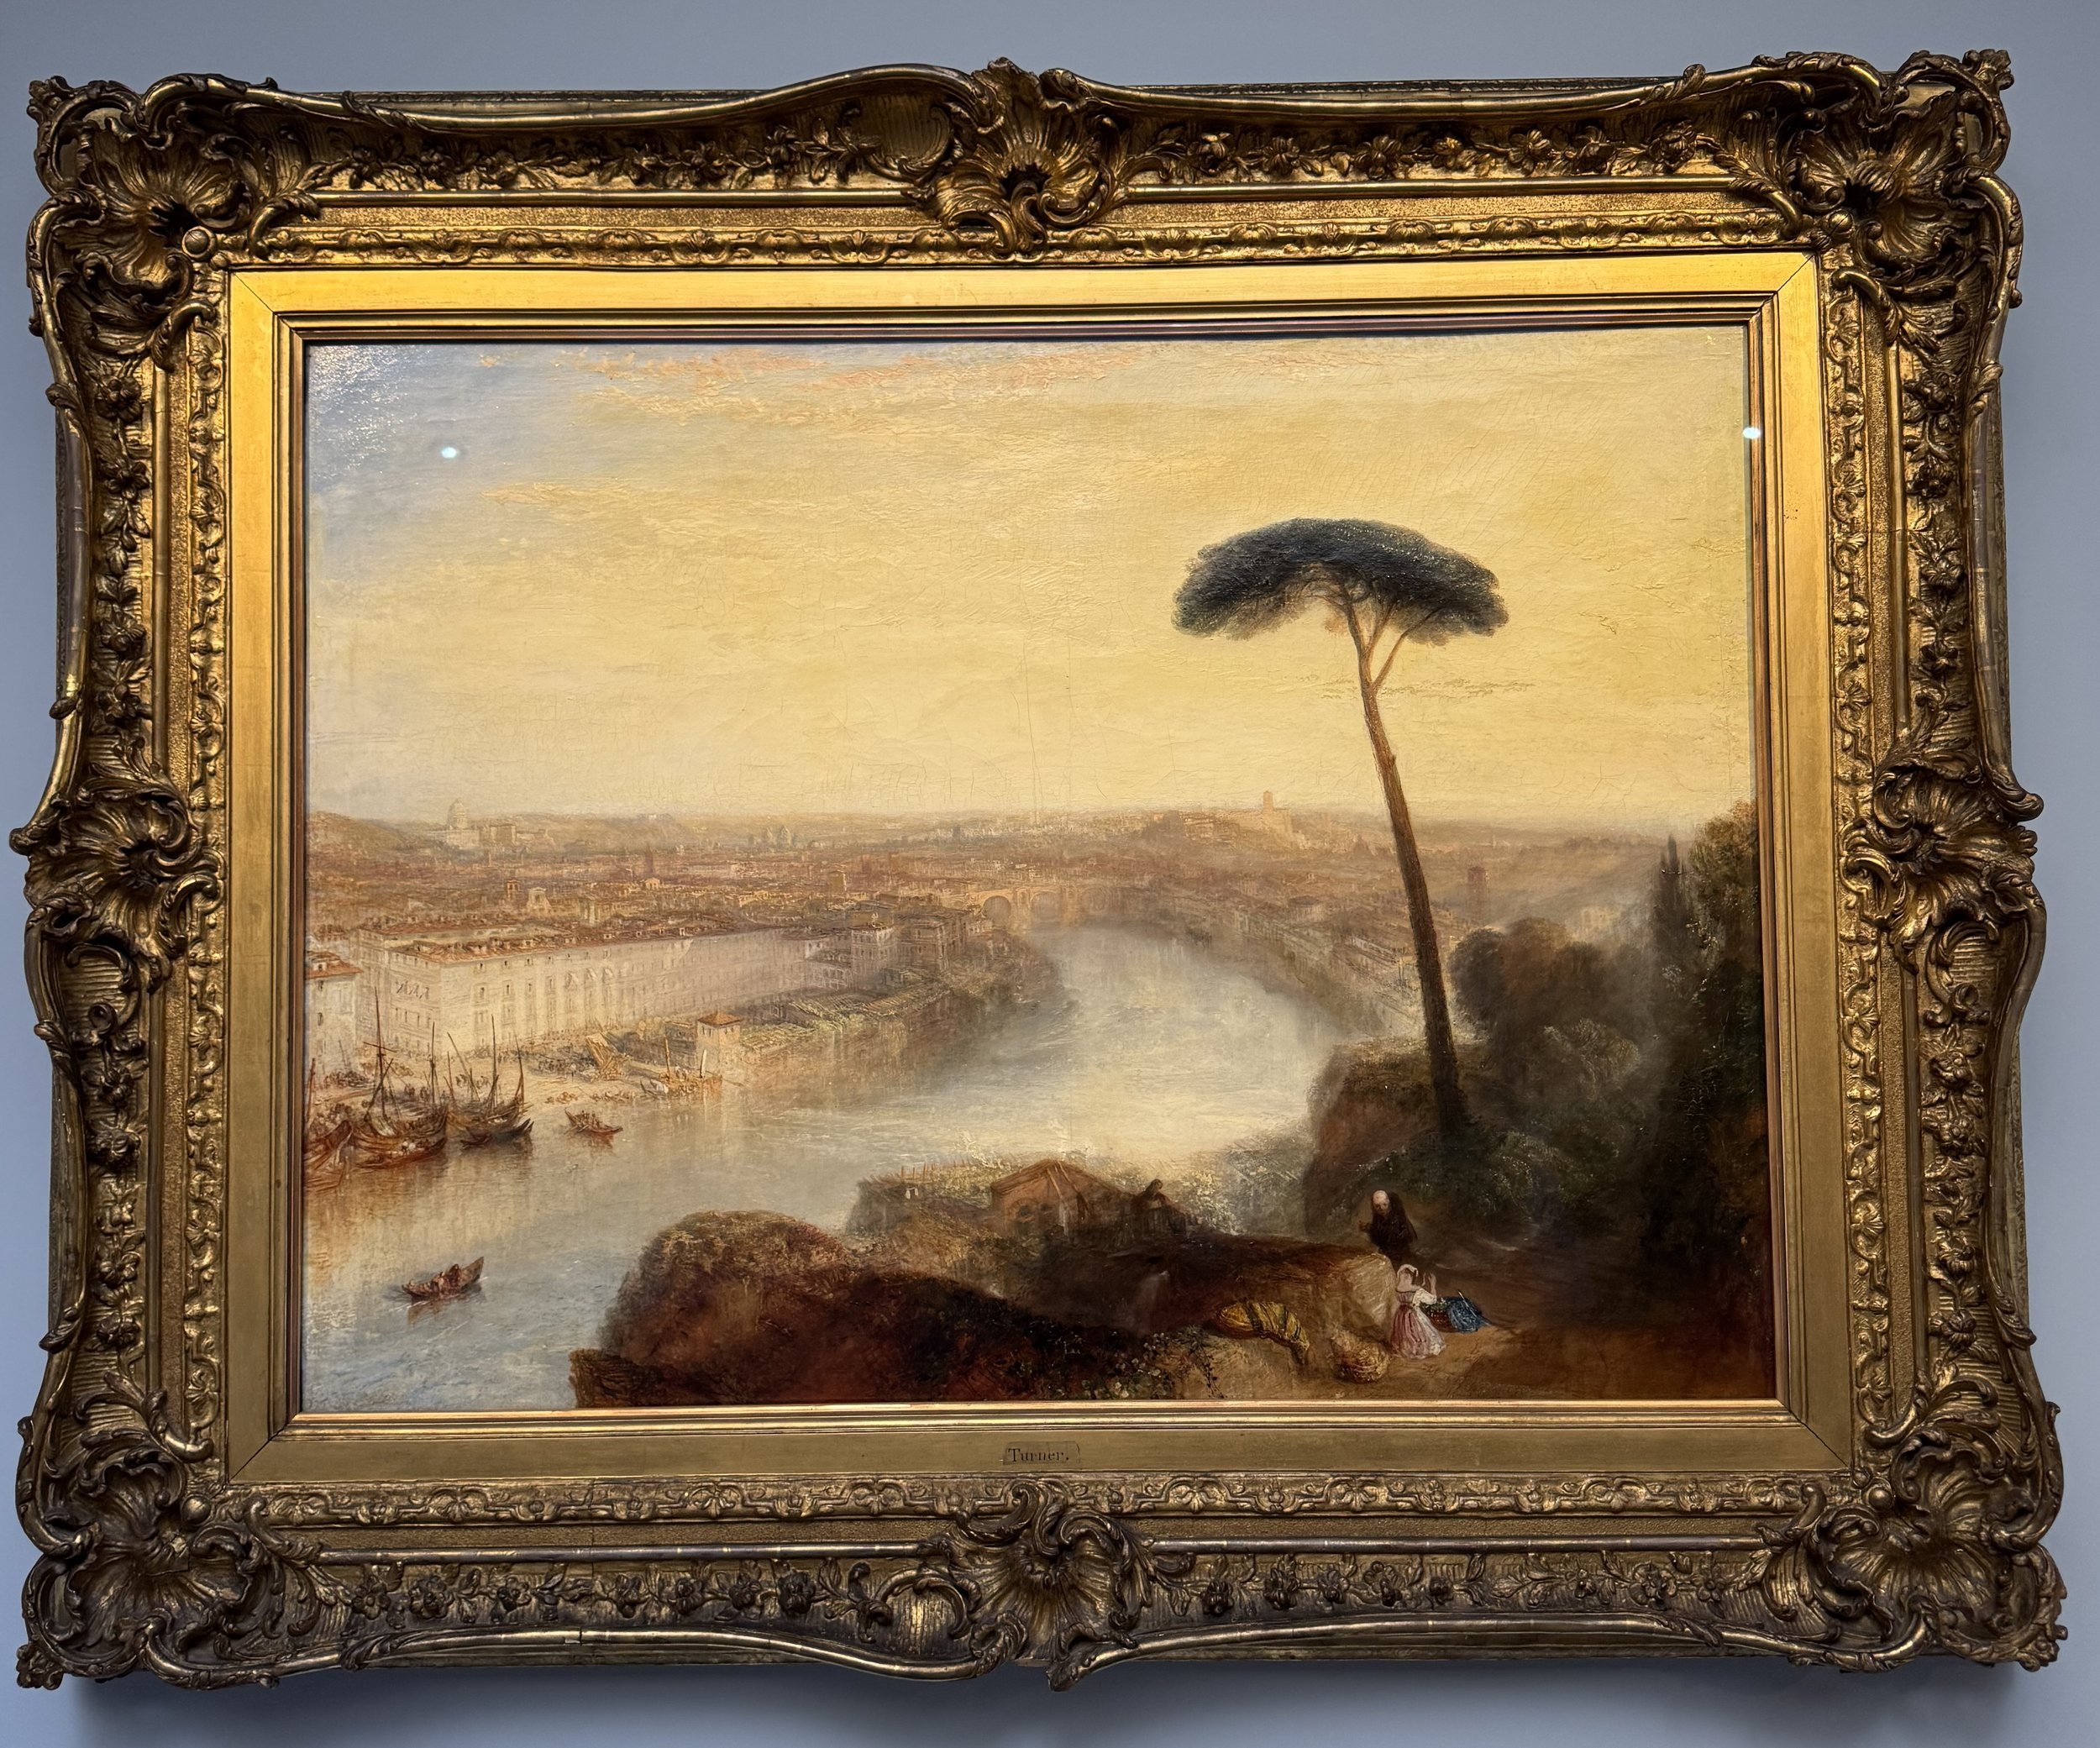
J.M.W. Turner, Rome, from Mount Aventine, 1835-36
Turner's Rome
Day 1 in London, and there is tons to see -- and then, as always, tons to say. Following visits to the National Gallery to view "Renoir in Love" and Gagosian to see the 130-piece exhibition of Magritte and his legacy, I dropped by Sotheby's sale exhibition, where one can see highlights coming to the block later in the season, such as J.M.W. Turner's magnificent Rome, from Mount Aventine, to be offered in December with an estimate in the region of $50 million. That's the highest estimate of anything presently in the building, and perhaps for good reason. We may expect to see bidding come from cross-sector trophy collectors, not limited to those specializing in Old Masters or British painting.
Takeaway #1 (more of a reminder): The upper echelons of the Old Master sector are supply-constricted. When major works in the sector are available, like two recent Canalettos, they soared. (The second highest auction sale of 2025 was a Canaletto.)
Takeaway #2: This one came to me from a conversation with a gallery visitor from Rome. She rightfully remarked that the Italian Culture Ministry has recently been spending serious money on paintings, including a seriously weak Caravaggio -- an artist I love, but Portrait of Monsignor Maffeo Barberini is hardly a lovable painting.
Although Turner was not Italian, she observed that having this extraordinary painting in Rome could be a source of pride and an important tourist attraction. And it's a point well taken. Perhaps the concept of cultural heritage is often too narrowly understood. Rome was *the* pivotal pilgrimage destination for generations of artists. It may not even be an "either / or", but having one of the best artistic products of this mandatory rite of passage by a non-Italian artist could be even more meaningful than a poor example of a great Italian artist's work.
The Strategic Collector
Last night, I had the pleasure of participating in the panel discussion, "The Strategic Collector: Art, Tax, and Philanthropy" in Washington, DC with esteemed colleagues, Channah Norman, Co-Chair of Art Law Practice at Shook, Hardy & Bacon L.L.P.; Ken Spruill, Director of Family Legacy & Wealth Education at Glenmede; and our outstanding moderator Mark R. Parthemer, Chief Wealth Strategist at Glenmede.
Our conversation covered a range of topics including family legacy, philanthropy, and succession; the circumstances that cause the need for appraisals; USPAP and IRS provisions; authenticity and provenance matters, including relevant case law, and much more. We had a lively conversation not only among us, but with an engaged, inquisitive audience of leaders from the arts and business communities.
Although I would love to share photos from the night, there simply are none to be seen, as the club is a phone-free, photo-free environment. As someone who is often fairly well glued to my phone, I surprised myself to realize how refreshing it was to have a moment to be briefly fully present, engaging fully with those in the room.
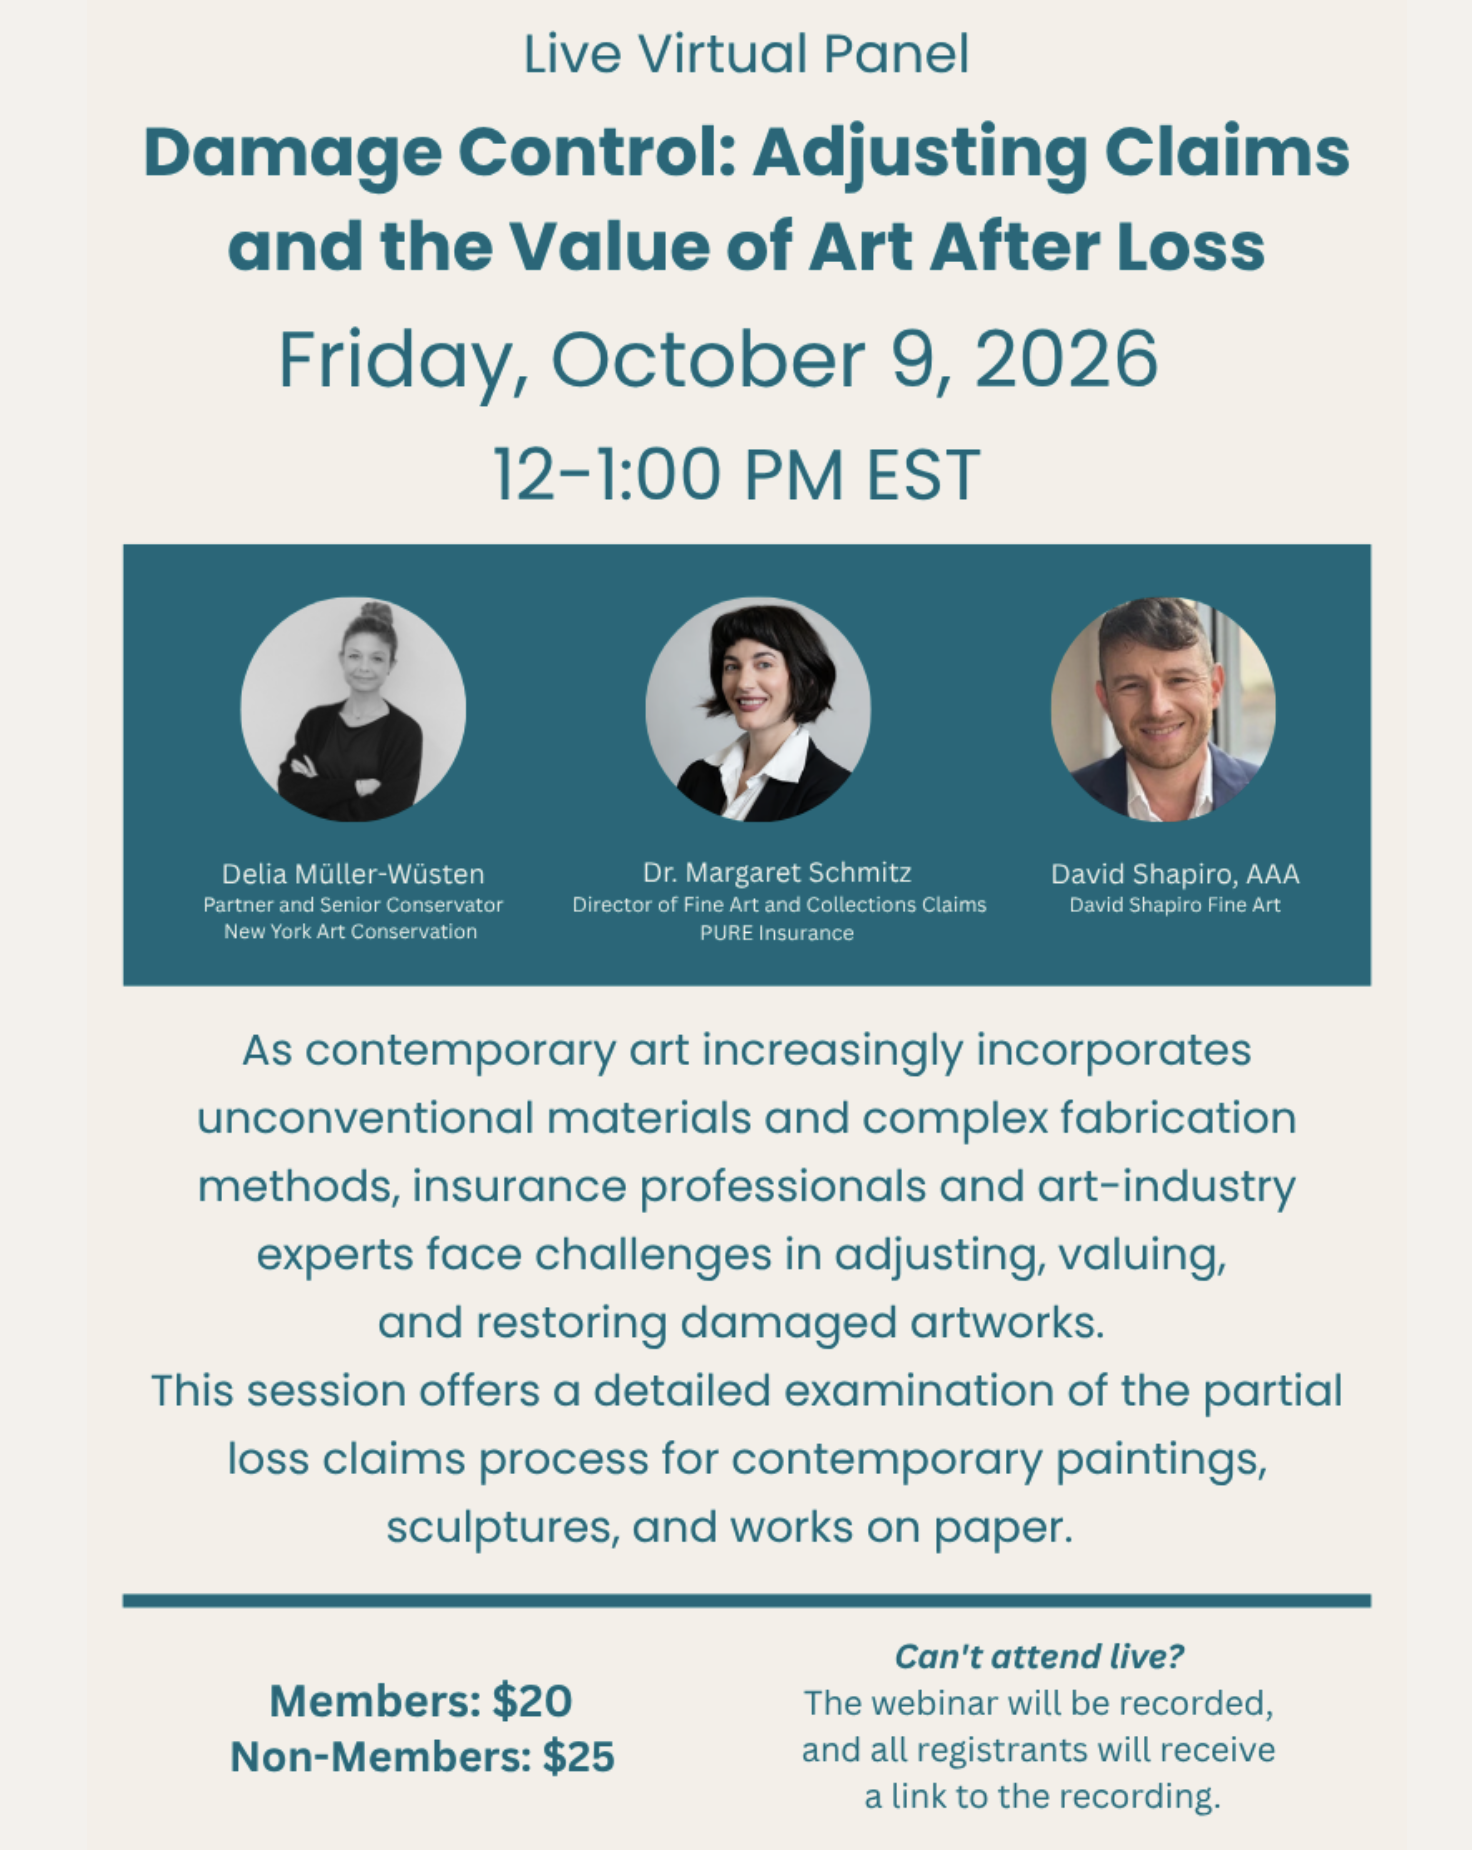
Damage Control: Adjusting Claims and the Value of Art After Los
Registration is open for this web-based panel hosted by the Appraisers Association of America.
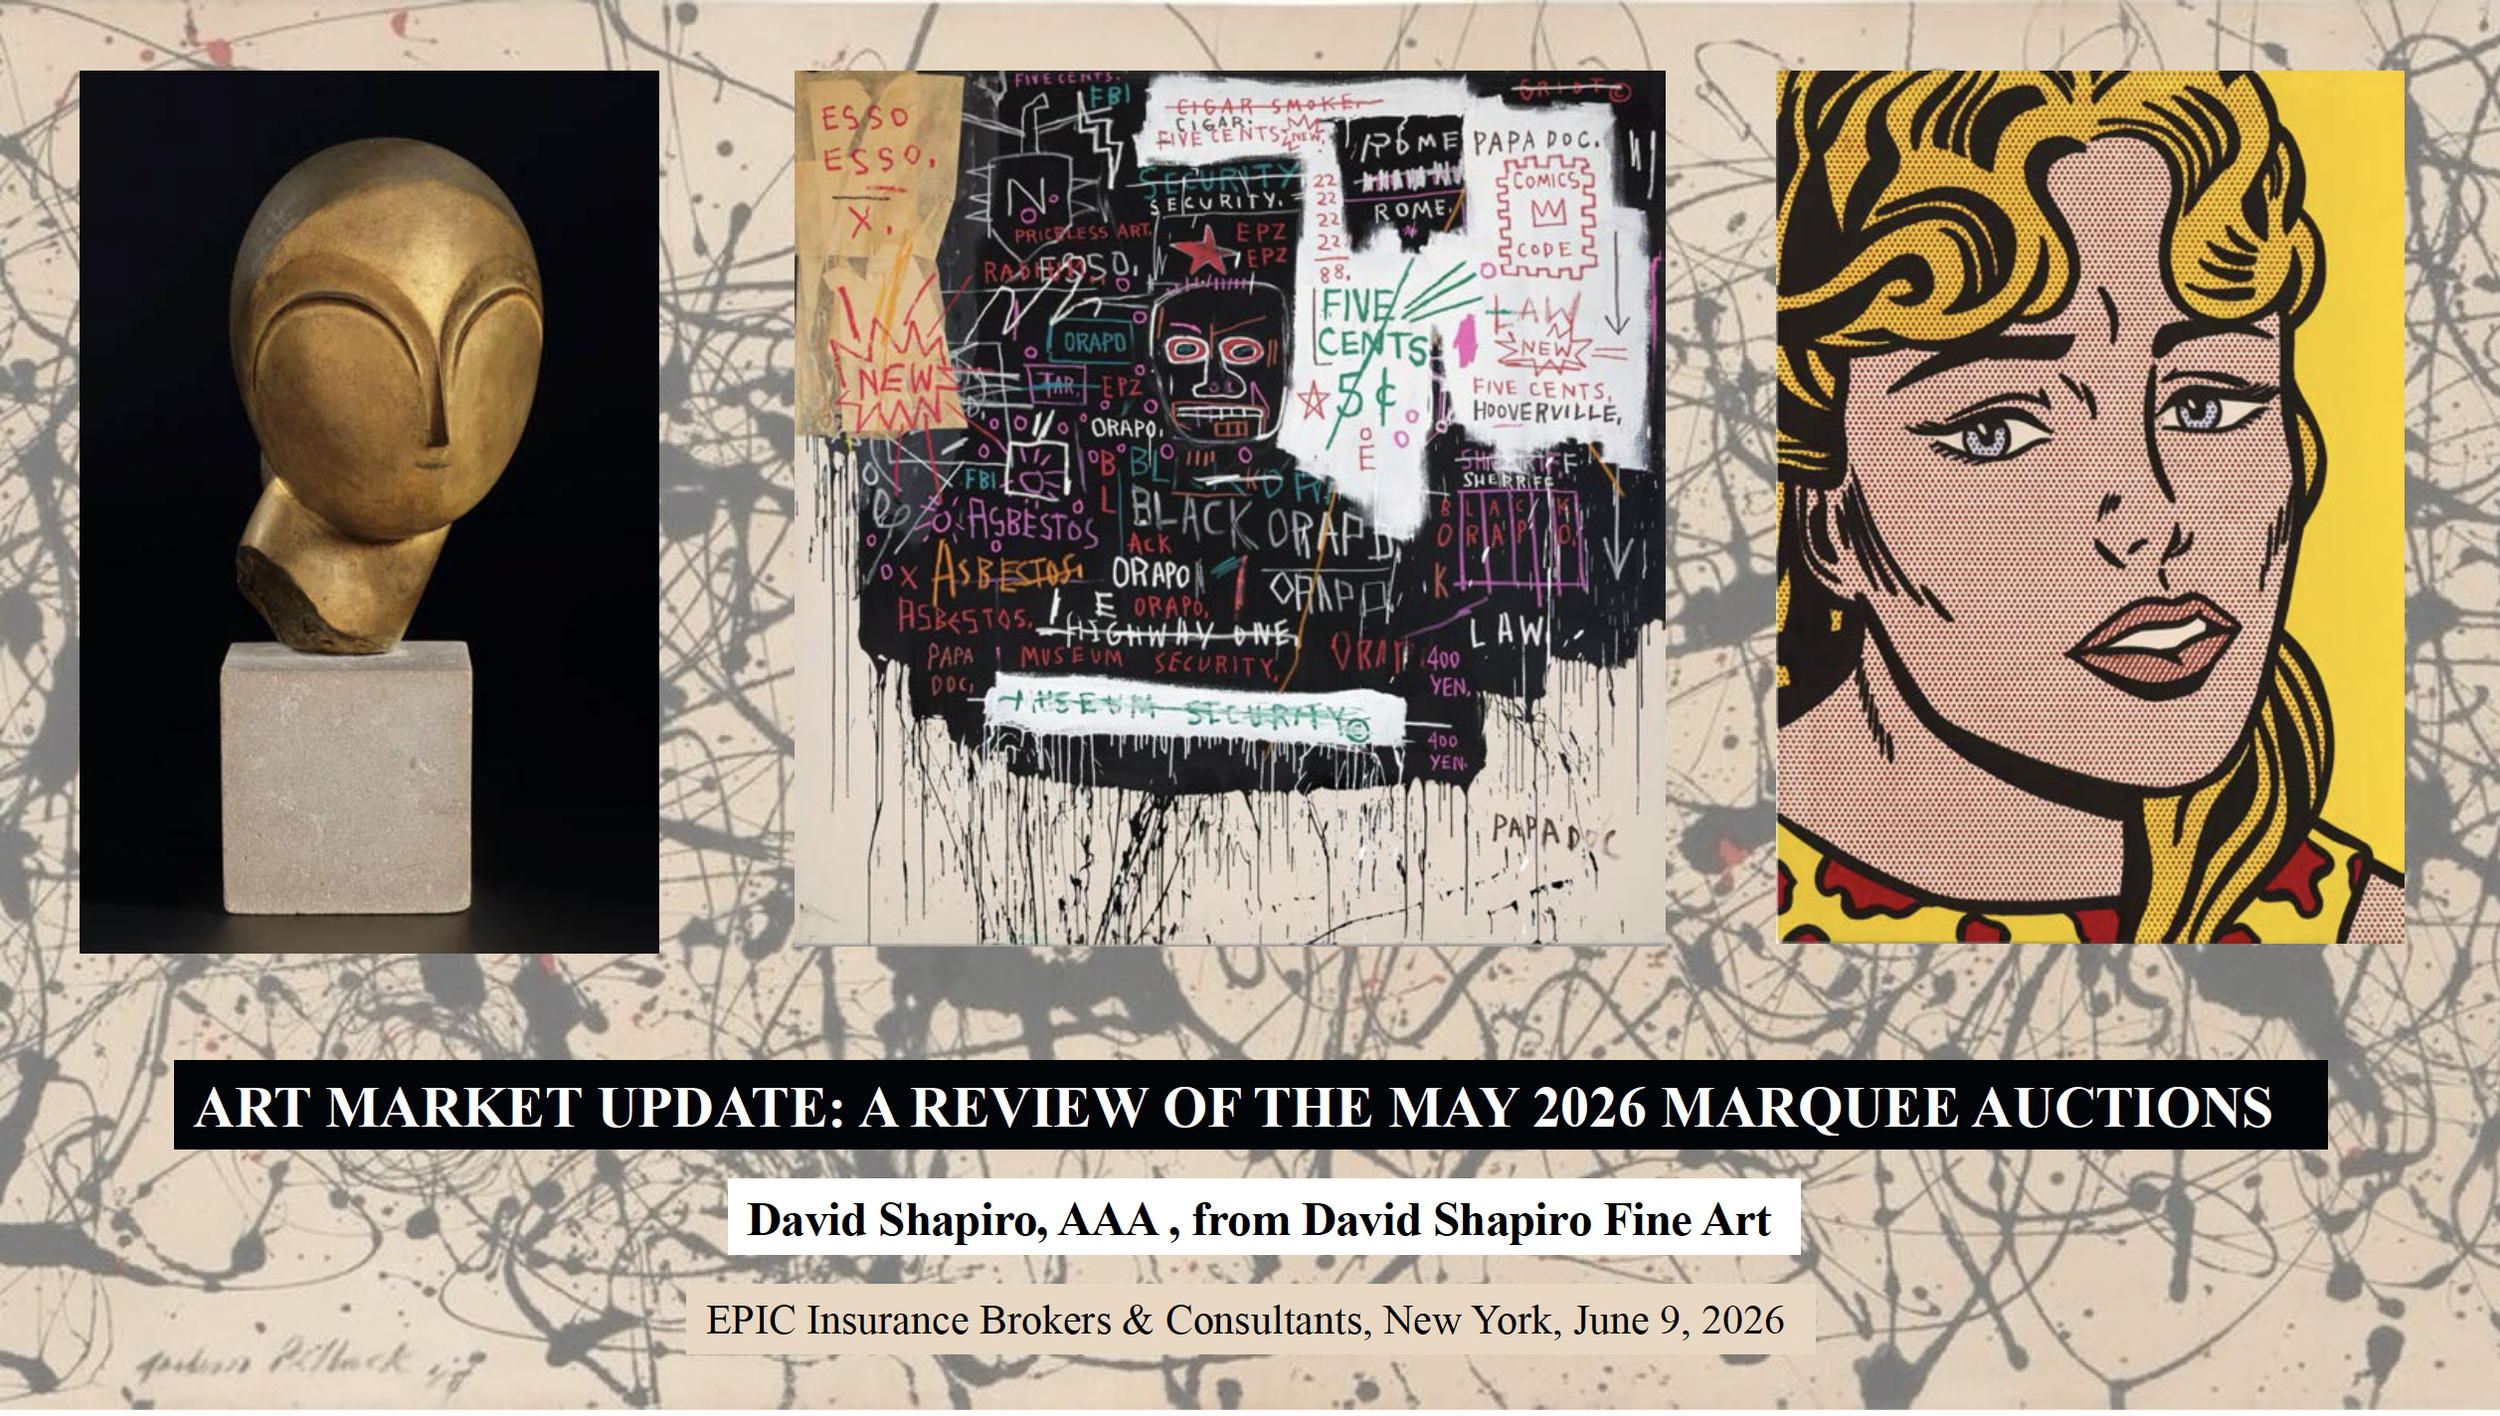
Presentation to EPIC Insurance Brokers & Consultants
A belated thank you to Alex Horowitz and his colleagues in the New York office of EPIC Insurance Brokers & Consultants for inviting me to speak last month. Among other topics, the presentation examined recent sales in the highest echelons of art market and their relevance to HNW + UHNW insureds.
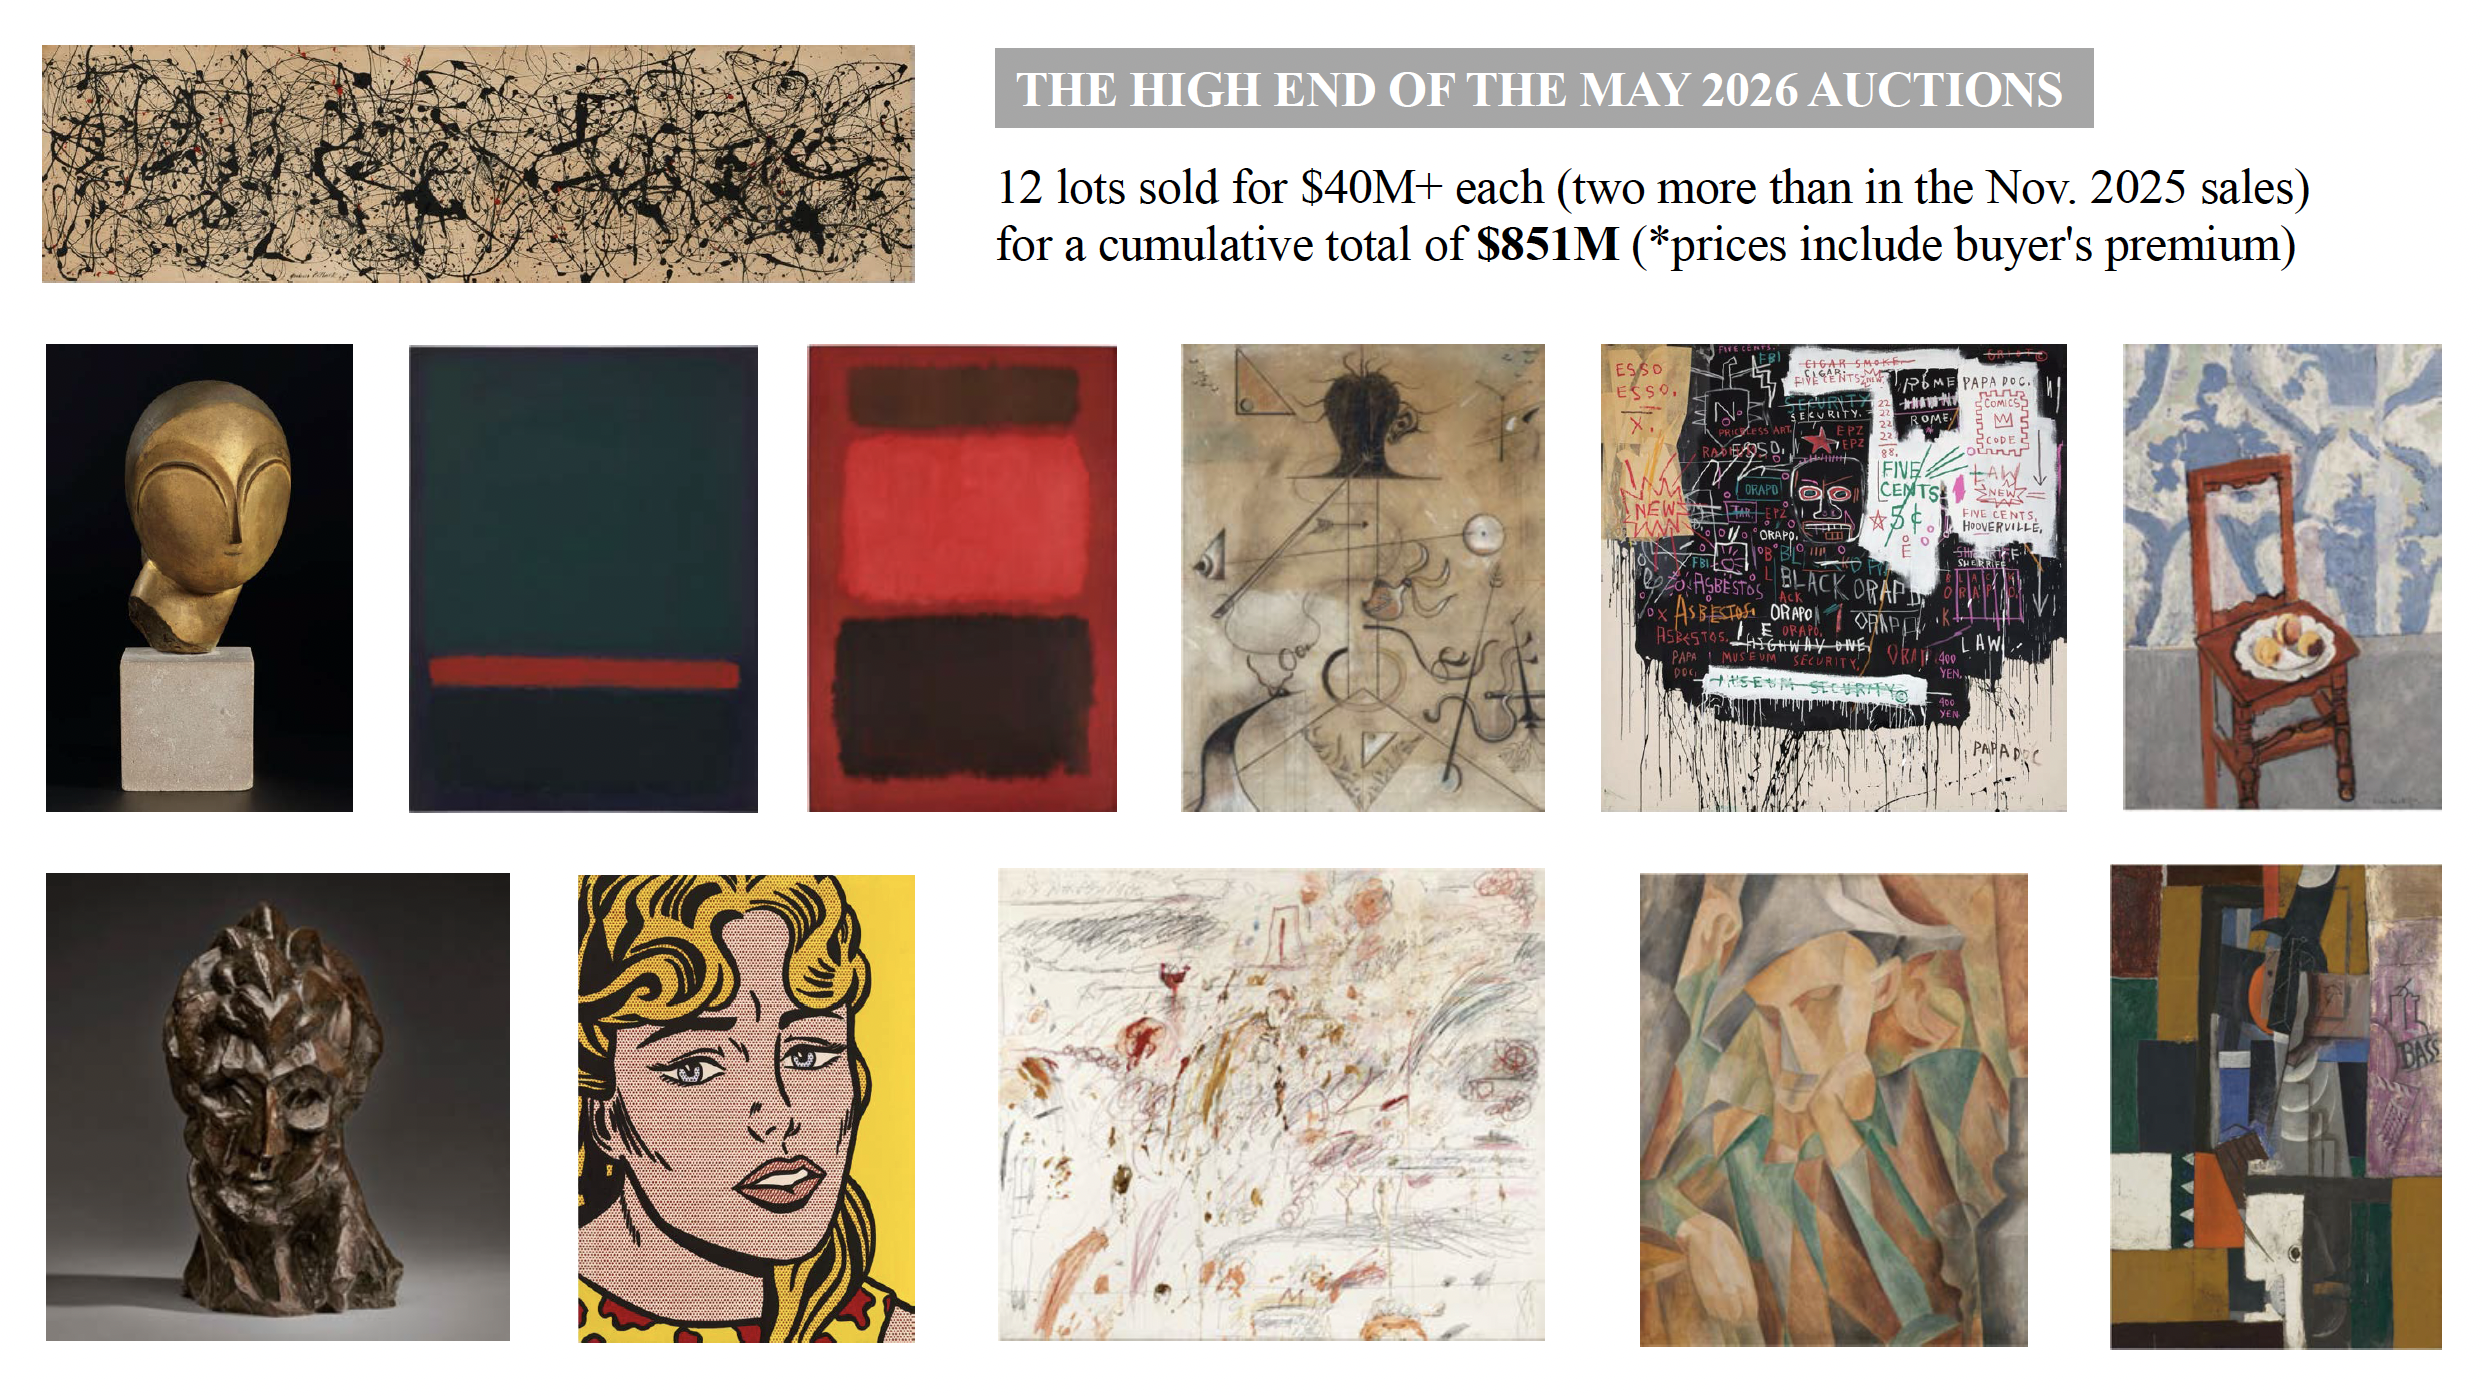
In May 2026 alone, 12 auction lots fetched $40M+ each, cumulatively realizing $851M (including buyer’s premium). All of these lots carried third-party guarantees.
The auctions were led by the sale of Jackson Pollock’s Number 7A for $181.2M, followed by Constantin Brancusi’s Danaïde, both at Christie’s, New York. Individual artist’s auction records in the $40M+ price tranche were also set for Miró and Rothko.
The presentation compared results this season with those in recent past marquee seasons (e.g., only three realized $40M+ auction lots in the entire first 10 months of 2025), and we had a lively discussion about the takeaways from these sales and recent trends for brokers and collectors alike.
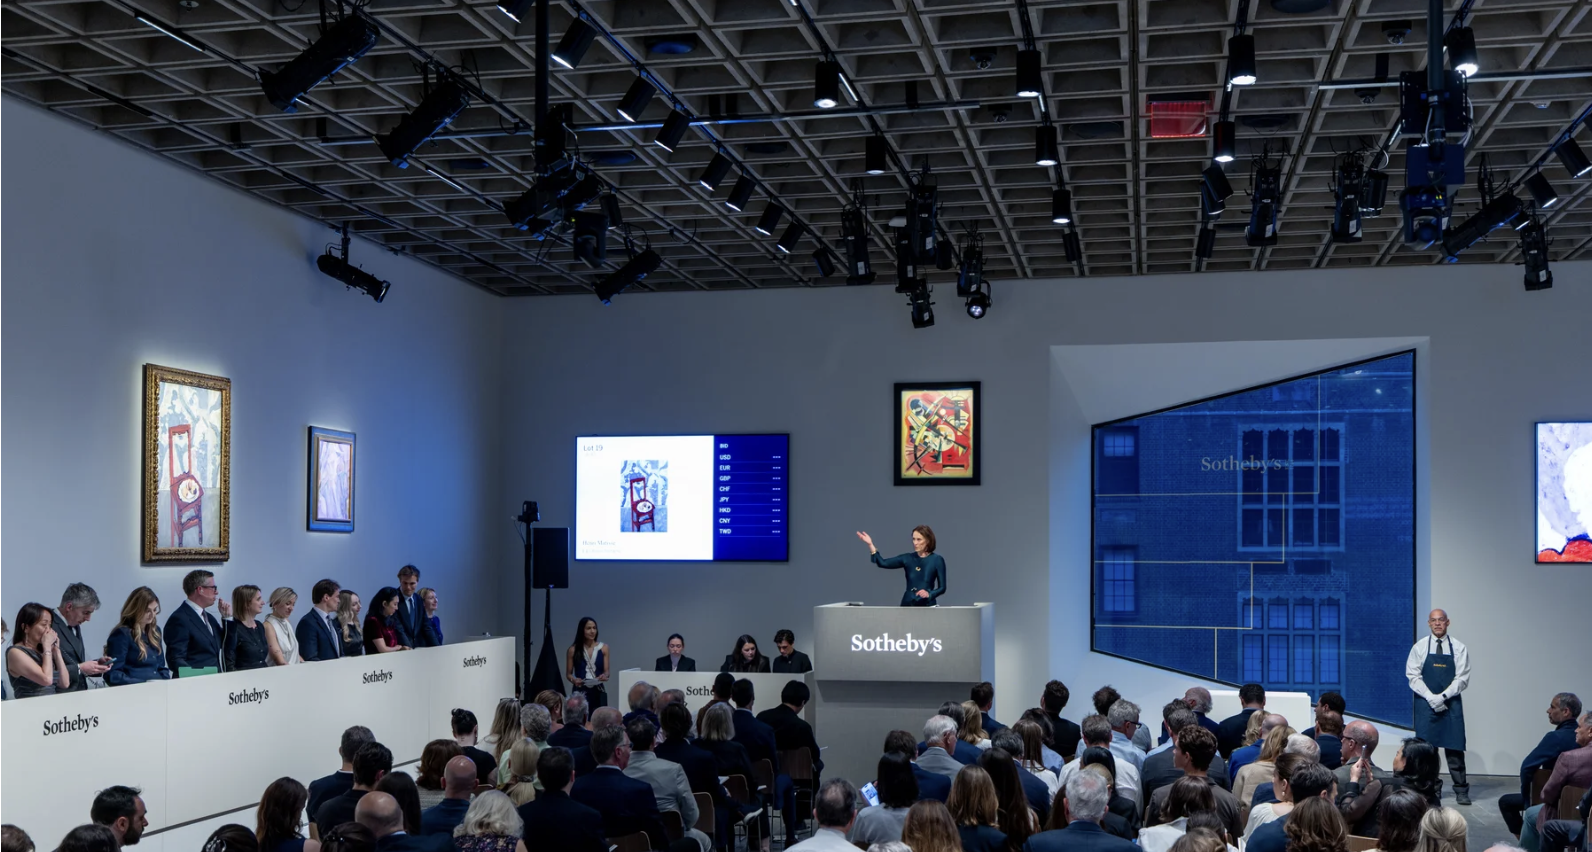
Quote in Artsy: "May’s Record-Breaking $2.5 Billion Auction Week, Explained"
My comments are included in Arun Kakar’s article, May’s Record-Breaking $2.5 Billion Auction Week, Explained, published this week in Artsy:
“‘New collectors may find that they are entering a market of cautious growth,’ said advisor David Shapiro. ‘They will be wise to learn lessons from recent burst speculative market bubbles, and instead, to prioritize, as much as possible, purchases of characteristic works by artists with proven standing and strong institutional support.’”
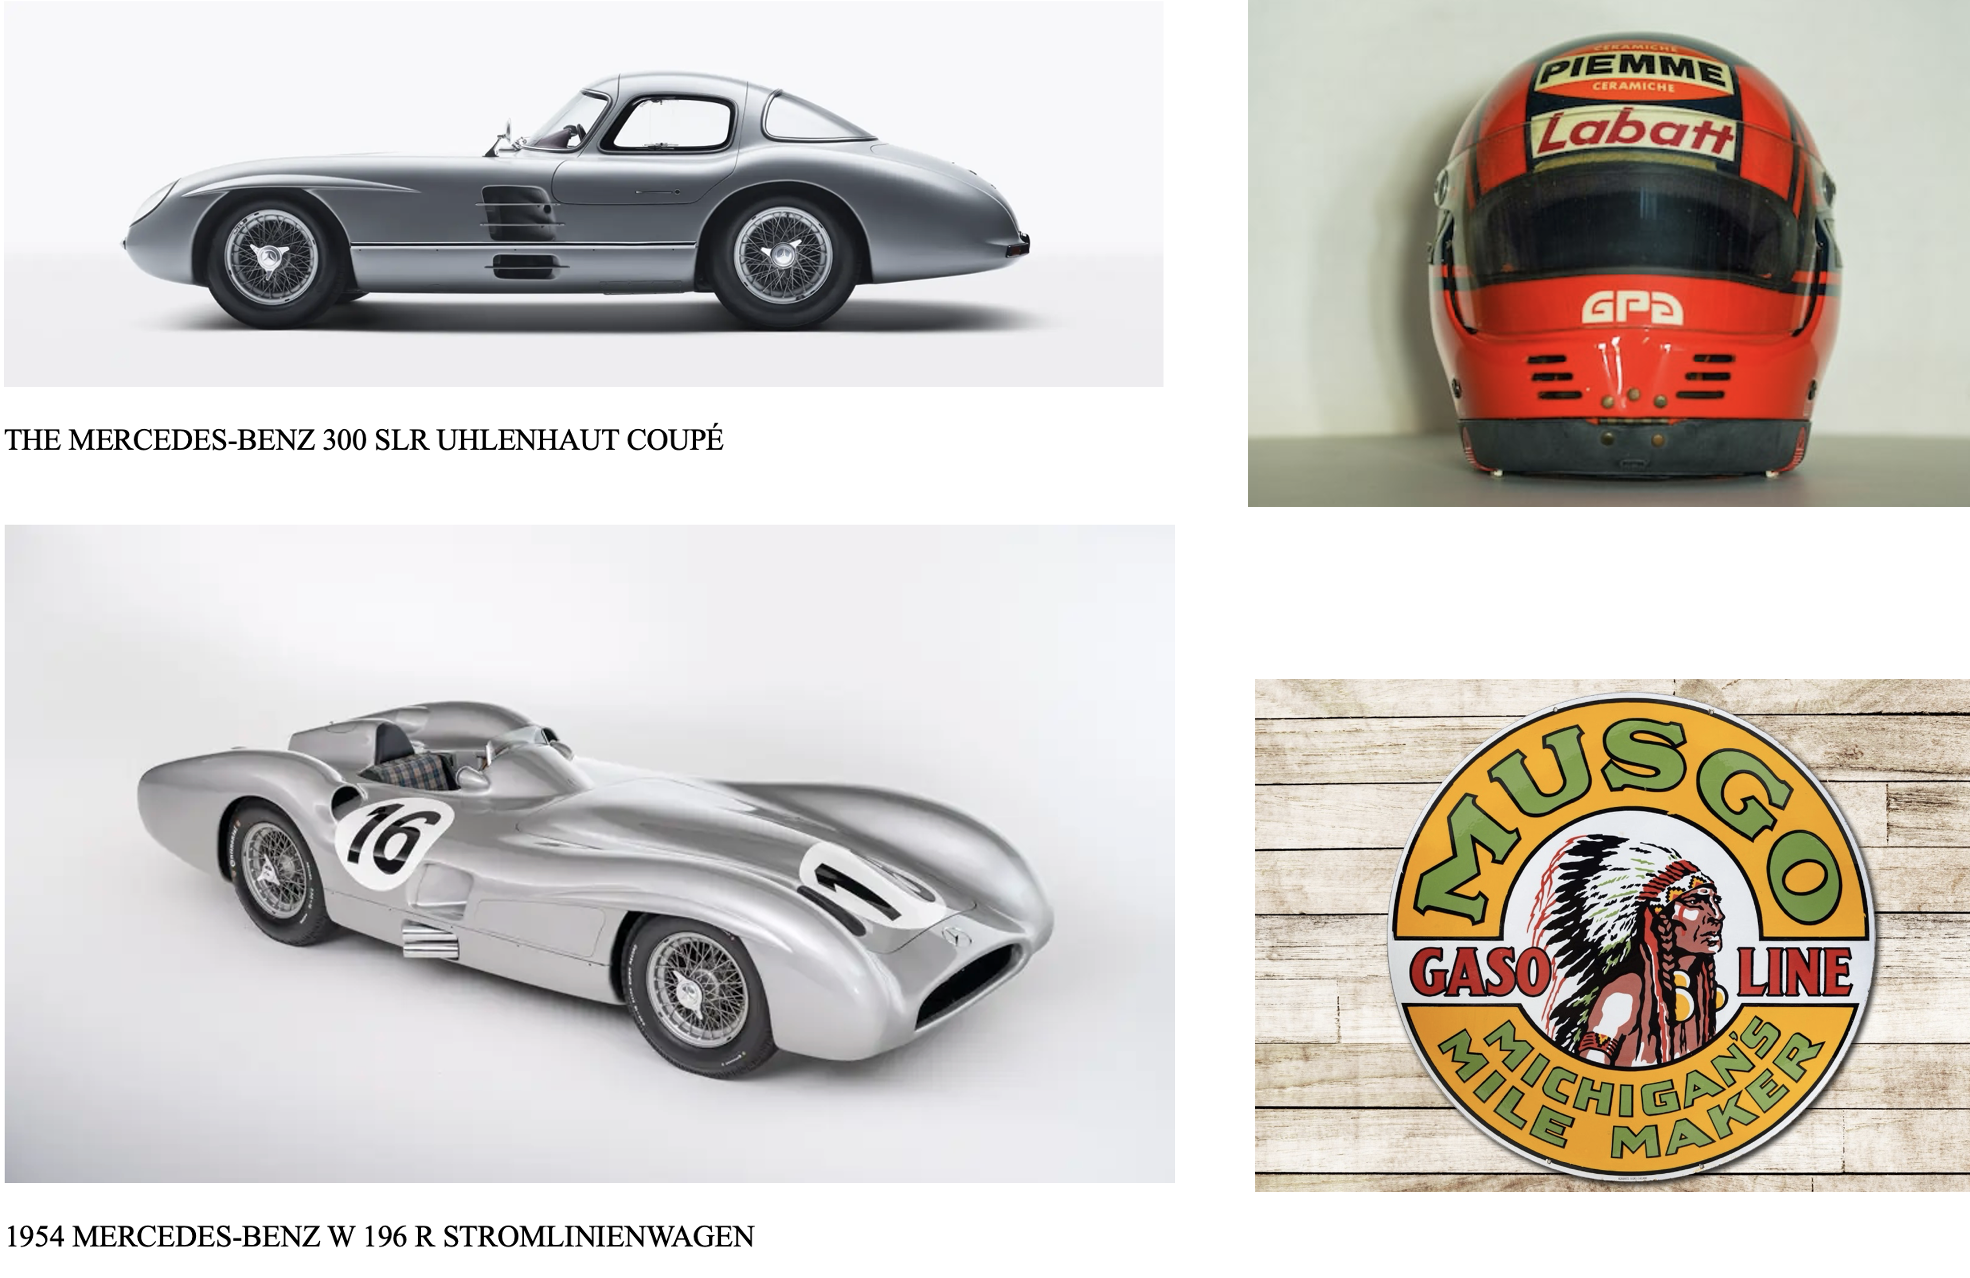
Gearing Up: Trends and Insights in Collector Cars and Memorabilia
It was so much fun to participate yesterday in the Private Risk Management Association (PRMA) session "Gearing Up: Trends and Insights in Collector Cars and Memorabilia", timed to the Greenwich Concours, alongside fellow panelists David Kinney (publisher of the Hagerty price guide), Erin Haydon, ARM of Markel International, and Kunal Kohli of Private Client Select -- and expertly moderated by Ashley Mehyo of Distinguished Programs! It was a lively conversation about topics such as the distinguishing features of collector cars, recent market trends, changing risk characteristics, and claims. Thank you ORNARE for generously hosting the event!
So often we are bound to our specialties (love the British word "specialisms") that we don't get a chance to engage in such profitable dialogue across sectors, but conversations such as these are precisely what enrich our knowledge and sharpen our tools. It's especially valuable for those of us who work largely in the HNW + UHNW space, which is largely and perhaps increasingly defined by a cross-sector approach to collecting.
For comparative perspective, prices realized in the high end of the collector car market are broadly in league with those in the highest tranche of the art market, even if the volume of trade for ultra-valuable collector cars is not as robust as it is for a similar strata of fine art.
The highest price ever realized at auction for a collector car is $143 million for the Mercedes-Benz 300 SLR Uhlenhaut Coupé at RM Sotheby’s in 2022, over $90 million higher than than the 2nd highest auction record for a collector car. This price level would be exceptional even for fine art and yet, that year, Andy Warhol's "Shot Sage Blue Marilyn" fetched $195 million at Christie's, i.e., $52 million *more* than the Uhlenhaut Coupé.
In 2025, the second highest auction price was realized for a collector car when the Mercedes-Benz W196 R Streamliner sold for $53.9 million at RM Sotheby’s. That year six works of art sold publicly above that level.
We also discussed the high end of the market for automobilia. Just last week, a helmet worn by the late Ferrari driver Gilles Villeneuve in his last Formula One race sold for $1.25 million, a world record for a racing helmet. In 2023, a Musgo Gasoline advertising sign sold for $1.5 million (15x its low estimate). Seen within the context of the surging market for collectibles (comics, trading cards, sports and entertainment memorabilia, etc.), one has to reason to expect further growth in this market subsector.
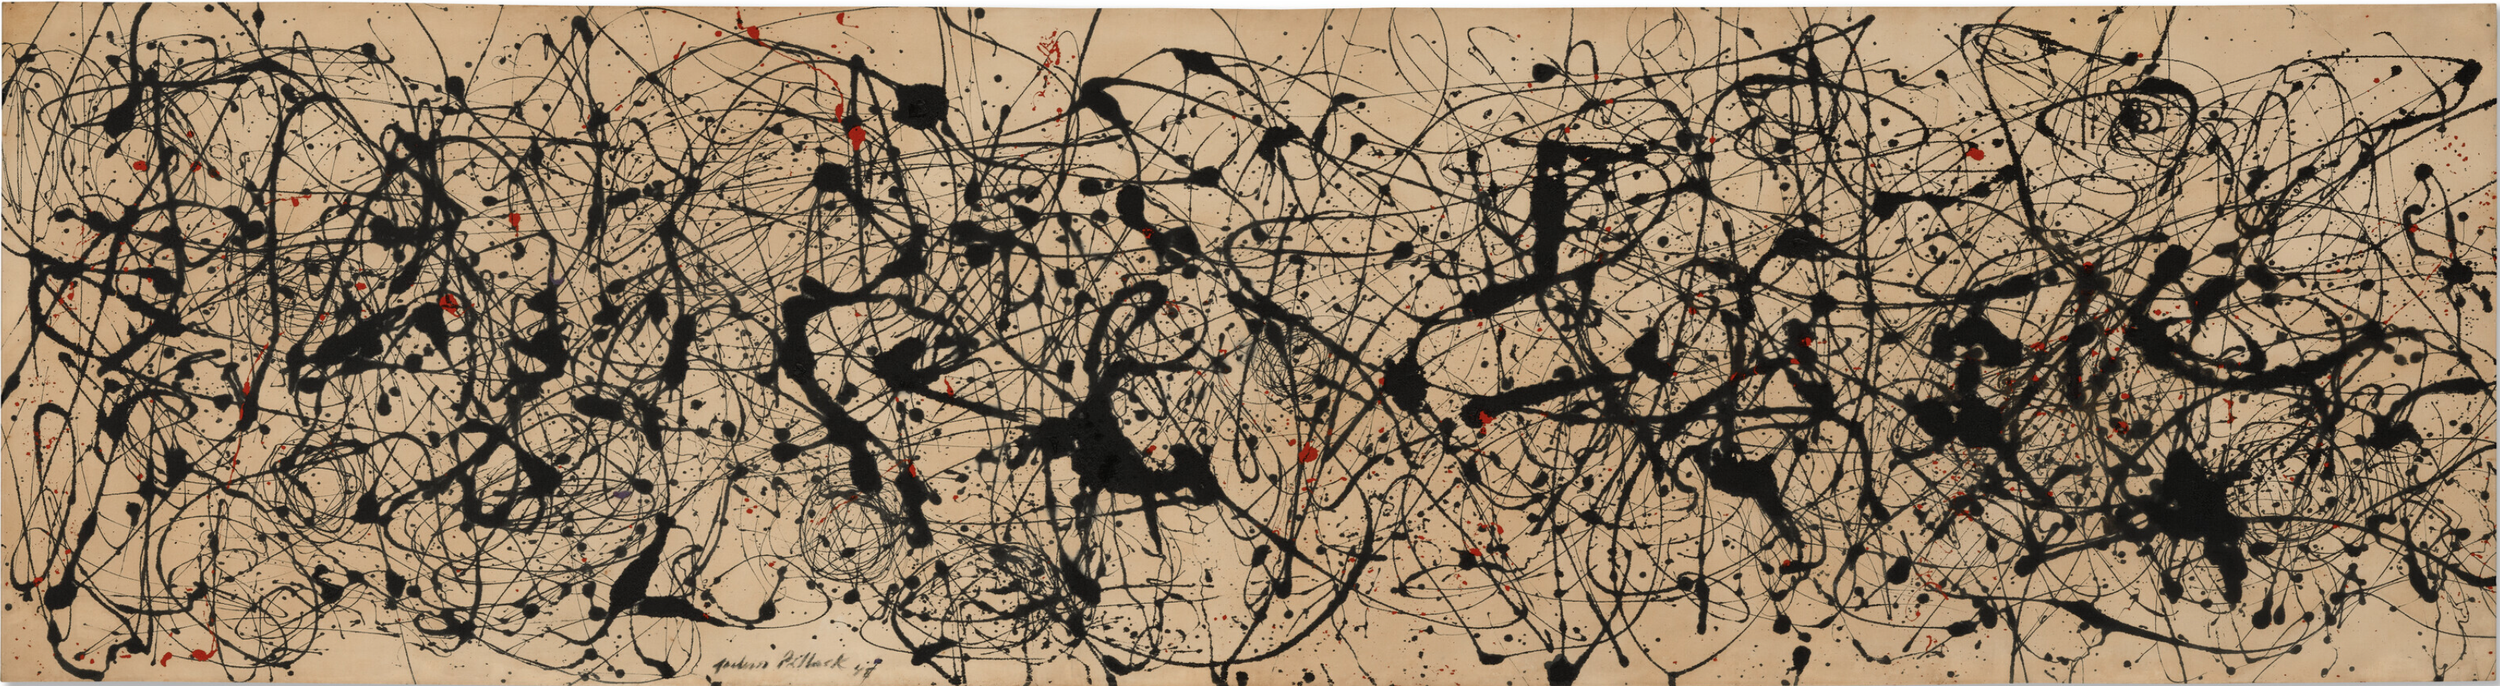
$40M+ sales in the May 2026 auctions
In the May 2026 auctions held over the past two weeks, 12 lots sold for over $40 million each (two more than in the Nov. 2025 sales) for a cumulative total of $851,022,500 (including buyer's premium). All of these $40M+ works were created in the twentieth century, and all were sold either at Christie's or Sotheby's with third-party guarantees (or "irrevocable bids" in Sotheby's terminology), so a strong high end was a foregone conclusion heading into the sales. Among this group, auction records were set for set for Jackson Pollock (who led the season), Constantin Brancusi, Mark Rothko, and Joan Miró.
In my calculations, 87.6% of the totals for $40M+ lots were from estate property, including the three highest lots, an even more pronounced pattern than what we saw in the November 2025 auctions (74%), further demonstrating that fluctuations in overall season-to-season results often depend more on circumstance-driven changes in supply at the high end than on changes in market confidence. However, to hedge against that comment a bit, there can be an element of discretion in when to sell estate property, as for Newhouse, in which works have been released to market periodically over time; clearly, they felt emboldened to sell key works now, and did so to remarkable results.
The top 12 in descending order of price realized:
1. Jackson Pollock, Number 7A (1948): $181,185,000 at Christie's (*auction record)
2. Constantin Brancusi, Danaïde (ca. 1913): $107,585,000 at Christie's (*auction record)
3. Mark Rothko, No. 15 (Two Greens and Red Stripe) (1964): $98,385,000 at Christie's (*auction record)
4. Mark Rothko, Brown and Blacks in Reds (1957): $85,780,000 at Sotheby's
5. Joan Miró, Portrait de Madame K. (1924): $53,535,000 at Christie's (*auction record)
6. Jean-Michel Basquiat, Museum Security (Broadway Meltdown) (1983): $52,717,500 at Sotheby's
7. Henri Matisse, La Chaise lorraine (ca. 1919): $48,405,000 at Sotheby's
8. Pablo Picasso, Tête de femme (Fernande) (1909): $48,480,000 at Christie's
9. Roy Lichtenstein, Anxious Girl (1964): $46,060,000 at Christie's
10. Cy Twombly, Untitled (1961): $45,485,000 at Christie's
11. Pablo Picasso, Arlequin (Buste) (1909): $42,640,000 at Sotheby's
12. Pablo Picasso, Homme à la guitare (1913): $40,885,000 at Christie's
IUA/LMA Joint Specie Claims event
It was a pleasure speaking last week in London in the International Underwriting Association (IUA) /Lloyd’s Market Association (LMA) Joint Specie Event, alongside Grace Best-Devereux, with moderation by Aliette Fenton-Sharp, both from Sedgwick. My presentation gave an overview of art appraisal with particular focus on the criteria that appraisers use for assessing partial loss in value (LIV) when works of art are damaged. Factors such as location of damage, stability of restoration, visibility of restoration, prior damage, relative rarity, and condition of comparable works can significantly influence the percentage of LIV assessed. Following my portion, Grace presented on the procedural aspects of adjusting fine art claims, including fascinating examples from the field. Then, we had a lively conversation on these subjects, prompted by insightful audience questions.
The Art Market, Appraisals and Insurance: What Brokers Need to Know Now
Please join me for a webinar on April 29 at noon (ET), “The Art Market, Appraisals, and Insurance: What Brokers Need to Know Now,” presented by the Pennsylvania Chapter of the Private Risk Management Association (PRMA).
Here is the summary:
As the art market continues to evolve, so too does the landscape of risk, valuation, and coverage. Join David Shapiro, AAA, of David Shapiro Fine Art Appraisal + Advisory, for an insightful session that begins with an art-market update—highlighting key trends, sales, and shifts shaping collector behavior today. From there, we’ll explore why these changes matter for brokers, underwriters, and insureds alike, examining the critical “nuts and bolts” of fine art appraisal for insurance purposes. You’ll gain a deeper understanding of how value is defined, the nuances of different appraisal types, and how accurate valuations support better coverage and claims outcomes.
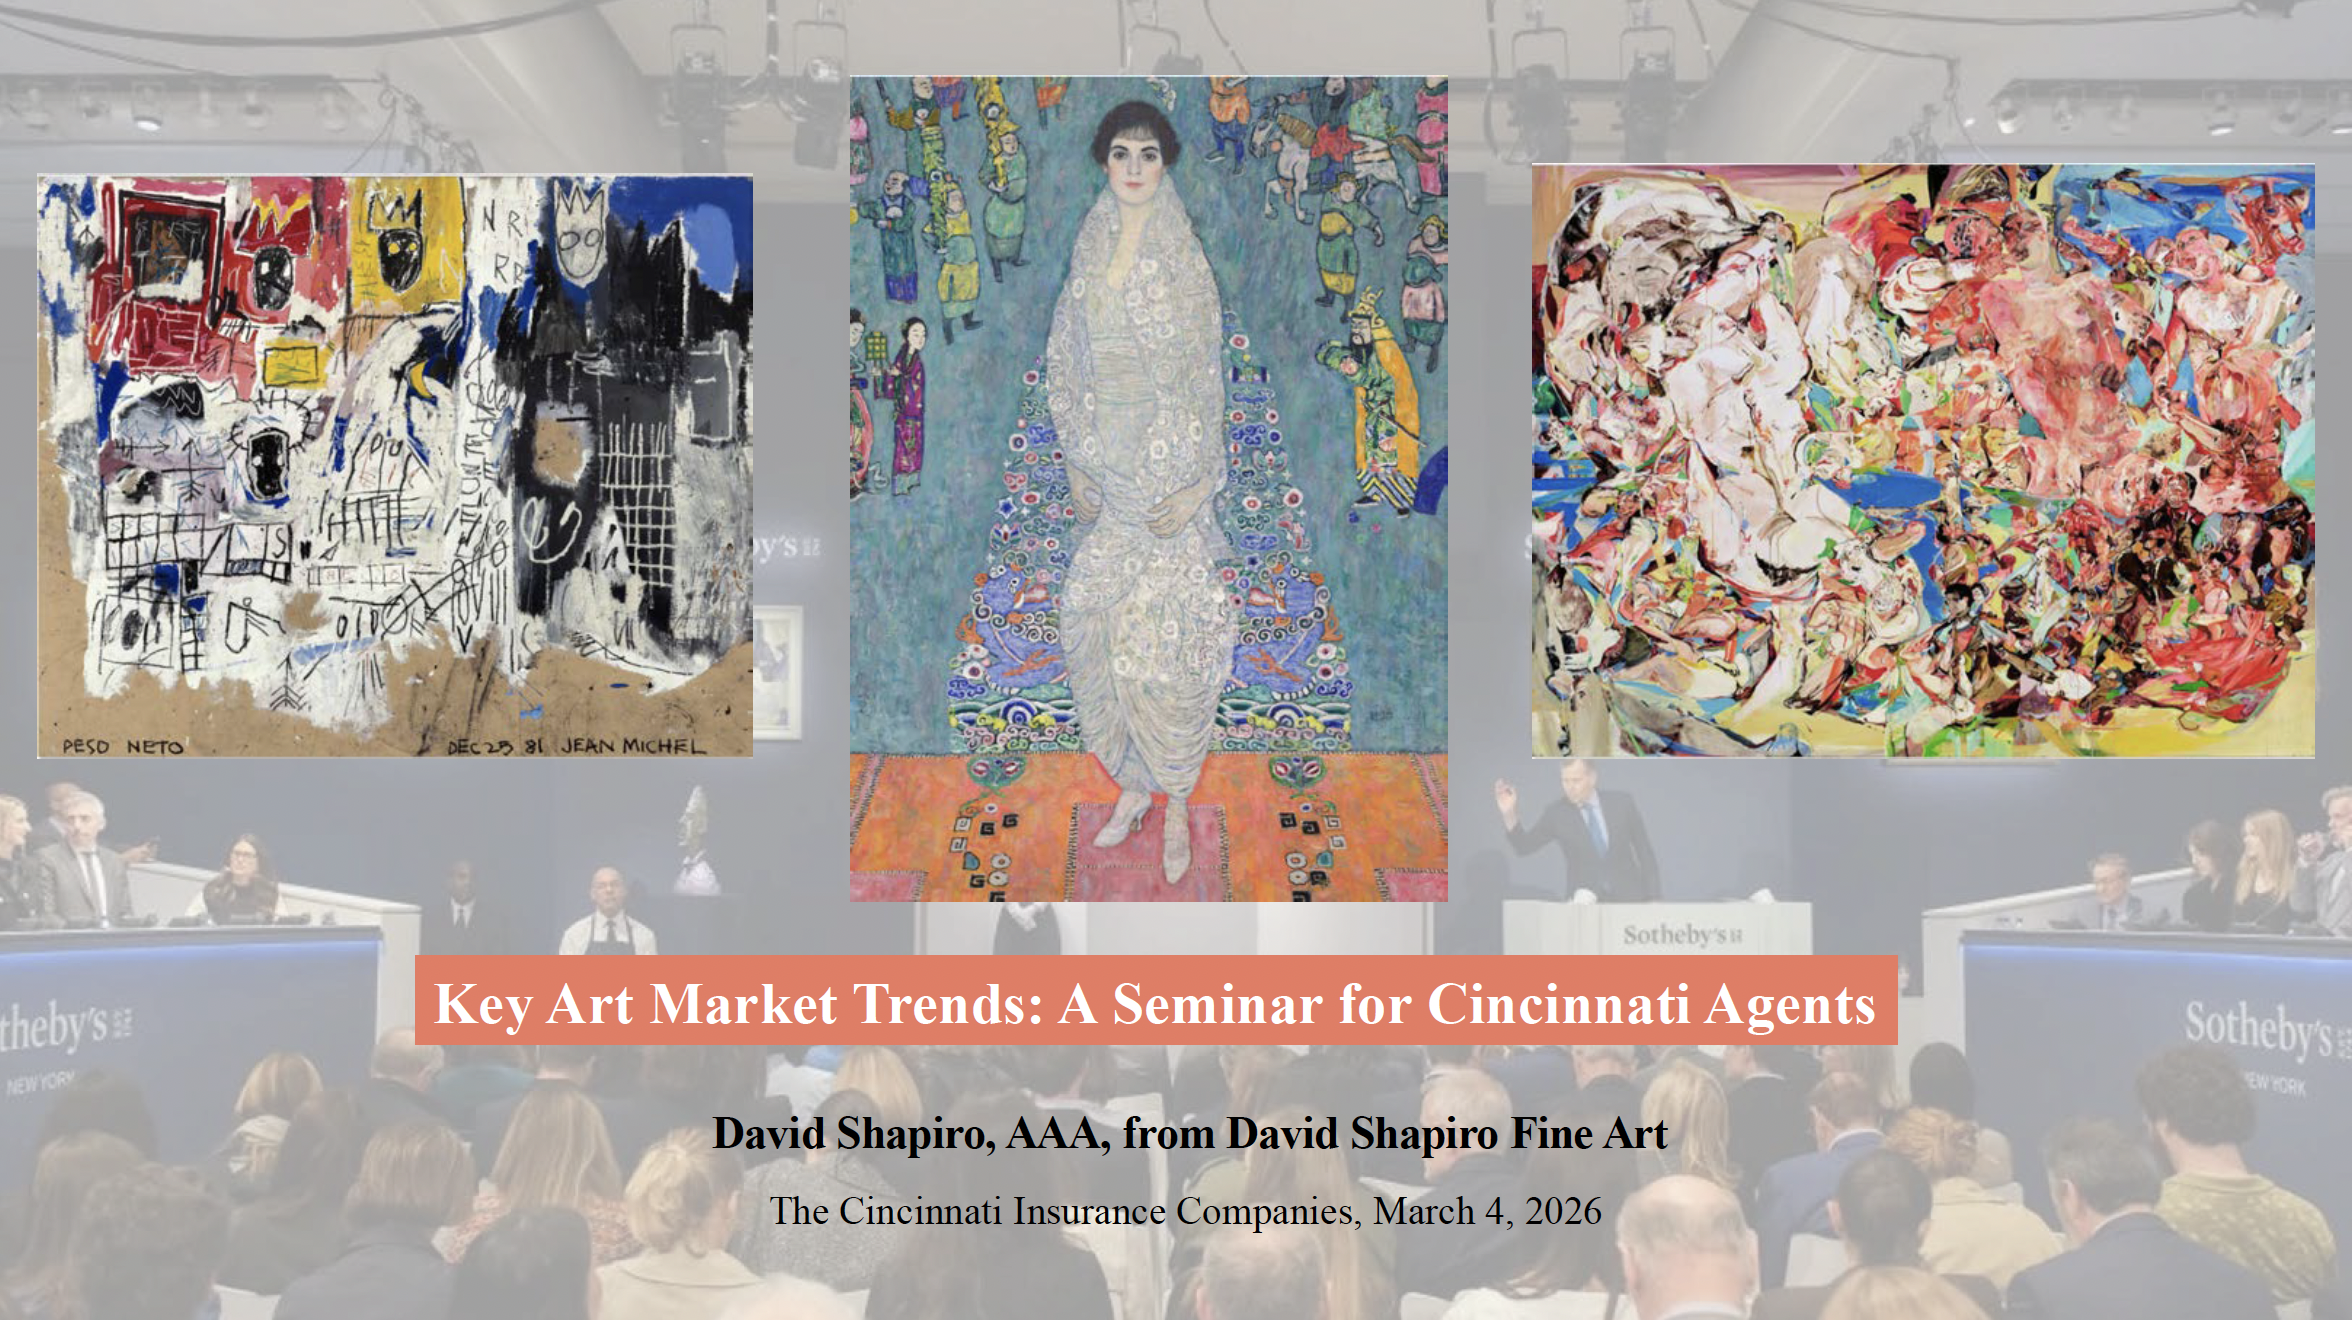
Key Art Market Trends: A Seminar for Cincinnati Agents
It was a pleasure giving this talk just now to underwriters at The Cincinnati Insurance Companies and their agents. Many thanks to Matthew Cluxton for organizing the seminar, and for everyone who shared their time. The presentation covered far-reaching ground including numerous new auction records ranging from Artemisia Gentileschi to Pokémon cards (and much in between), private auctions in the stratosphere, third-party guarantees, swings in the market for emerging art, and of course the insurance ramifications of market moves and best practices for appraisal (and reappraisal). It was a lively hour spent well!
PRMA blog post: The Art Market Is Moving Fast: Here’s Why Appraisals and Insurance Matter More Than Ever
Following my recent webinar, Private Risk Management Association (PRMA) summarized the program in a blog post, "The Art Market is Moving Fast: Here's Why Appraisals and Insurance Matter More Than Ever".
Their blog post covers topics in the presentation including:
-- A market of extremes
--The rise and fall of emerging artists
--The risk of underinsurance
--Appraisal standards
--The expanding world of collectibles
--The benefits of staying proactive
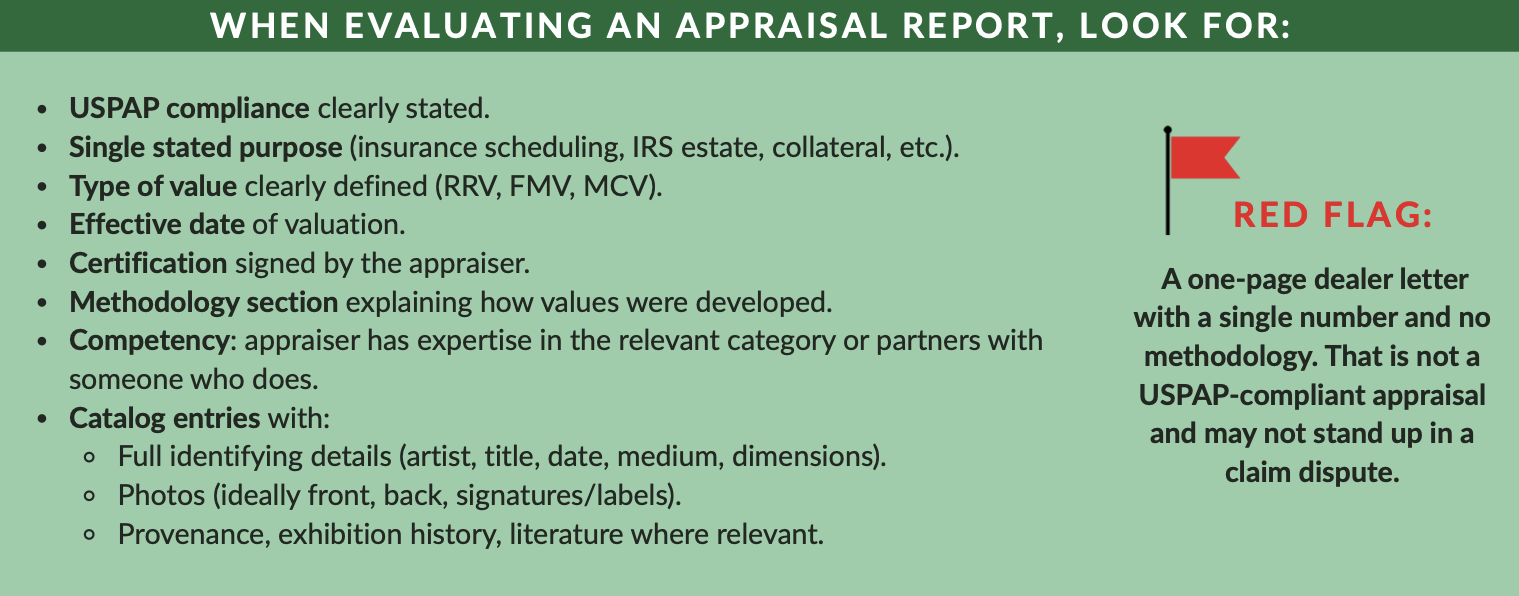
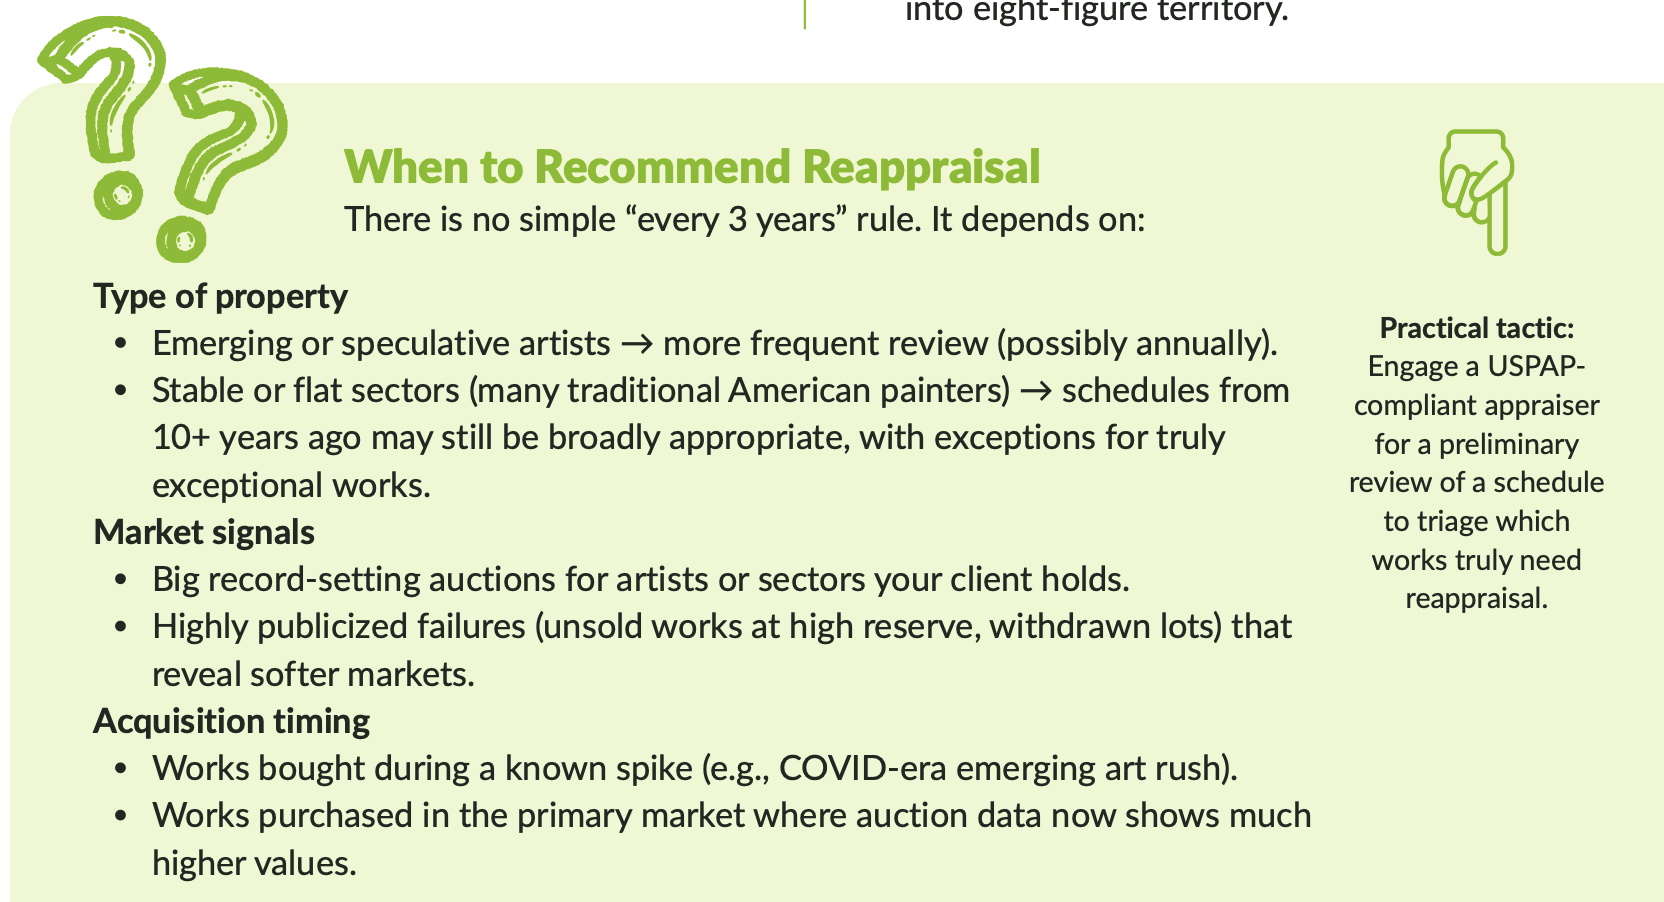
Drawing from the webinar, PRMA has also assembled an Art Market Volatility Watchlist, alerting brokers, underwriters, collectors, and their advisors to some key points regarding shifting values in the present market.
Recommendations in this Watchlist include the following, concerning what to look for in an appraisal report and when works of fine art should be reappraised for insurance purposes.
Shook, Hardy & Bacon: Art Law Bulletin: Art Basel Miami Beach: An Art Appraiser’s Perspective
It was a pleasure to contribute to the December 2025 edition of Shook, Hardy & Bacon's “Art Law Bulletin.” This feature, assembled by Channah M. Norman, Tristan L. Duncan, and Alicia J. Donahue, is titled Art Basel Miami Beach: An Art Appraiser’s Perspective. My contribution is as follows:
The Artsy Art Basel Miami Beach wrap article says that the highest sale at the fair was Andy Warhol’s “Muhammad Ali” (1977) for $18 million at the Lévy Gorvy booth, and ARTNews says that the most expensive work on offer at the fair was a 1979 untitled Joan Mitchell on offer from Richard Gray Gallery for $18.5 million, though the report from Art Basel itself states that David Zwirner sold its Mitchell, “Sunflowers” (1990-91), for $20 million.
In fact, none of the above were the highest offerings at the fair. Gagosian was offering Picasso’s “Surreal Boy with a Basket” (1939) for $22 million, and Van de Weghe was offering Jean-Michel Basquiat’s “Onion Gum” (1983) for $21.5 million. These were the highest asking prices that I observed at this edition of Art Basel.
To my knowledge, the press has not commented on whether the Picasso or the Basquiat sold at the fair, and indeed, this may never be known, considering that dealers, being protected by the Privacy Rule in the Gramm-Leach-Bliley Act, have no legal obligation to disclose any of their realized prices at art fairs or otherwise, even while local laws may require them to conspicuously publish asking prices at the point of exposure. Although dealers may offer information about realized prices to journalists or in exit surveys issued by a fair, doing so is voluntary. Consequently, reports of completed transactions at art fairs are necessarily approximate at best, unlike published results of sales at public auction, which offer clear indicators of the market.
Whether or not the most expensive works on offer at Art Basel found buyers that week, it is worth noting that even at this fair, which is the largest and generally considered the most significant U.S. art fair, the highest end of offerings capped out around $20 million, which could be considered within range for a major art fair, notwithstanding occasional higher outlier offerings. This level is considerably lower than the high end of the auction market.
By comparison, in the November 2025 marquee auctions in New York, 19 lots fetched prices in excess of $18 million each (including buyer's premium), among which 10 lots sold above $40 million. Among these, six lots sold above $50 million, namely three Klimt paintings, a van Gogh, a Rothko, and a Kahlo. Klimt’s “Portrait of Elisabeth Lederer” fetched $236.4 million at Sotheby’s, the second highest auction price ever realized for a work of art and the highest for a work of modern art at auction.
Adjacent to the fine art sphere, the high end of the auction market has continued to witness phenomenal results in December 2025, most notably the sale of a Fabergé egg for $30.2 million at Christie’s in London and the sale of François-Xavier Lalanne's Hippopotamus Bar for $31.4 million at Sotheby’s in New York, an all-time auction record for the design sector.
The soaring high end seen in November was in no small part driven by circumstance: among the top 10 lots in the November 2025 auctions, 75% of total sales (by value) comprised estate property, the timing of which is beyond anyone's control. However, there were also significant discretionary sales among the highest ($18 million+) tier, including the sale of the Kahlo, “El sueño (La cama),” for $54.7 million, which set the record for any female artist at auction and any Latin American artist at auction. We simply did not see such offerings at Art Basel.
Anecdotal as they may be, reports indicated brisk sales in the middle market at Art Basel Miami Beach this year. One may speculate as to whether the buoyant auction market of November 2025, in which overall totals far surpassed those of equivalent sales in recent seasons, primed the mood for the fair such that private sales were easier to effect. Although the record sale of a $236 million Klimt from the Lauder estate may have very little direct correspondence to the relative volume of six-figure transactions that dealers may make at the fair, it is indeed reasonable to speculate that mood may have been a factor, though shifts in market behavior often owe to a variety of cultural and economic factors, and direct causation can be difficult to trace.
"Icons" at Sotheby's: A private sales story
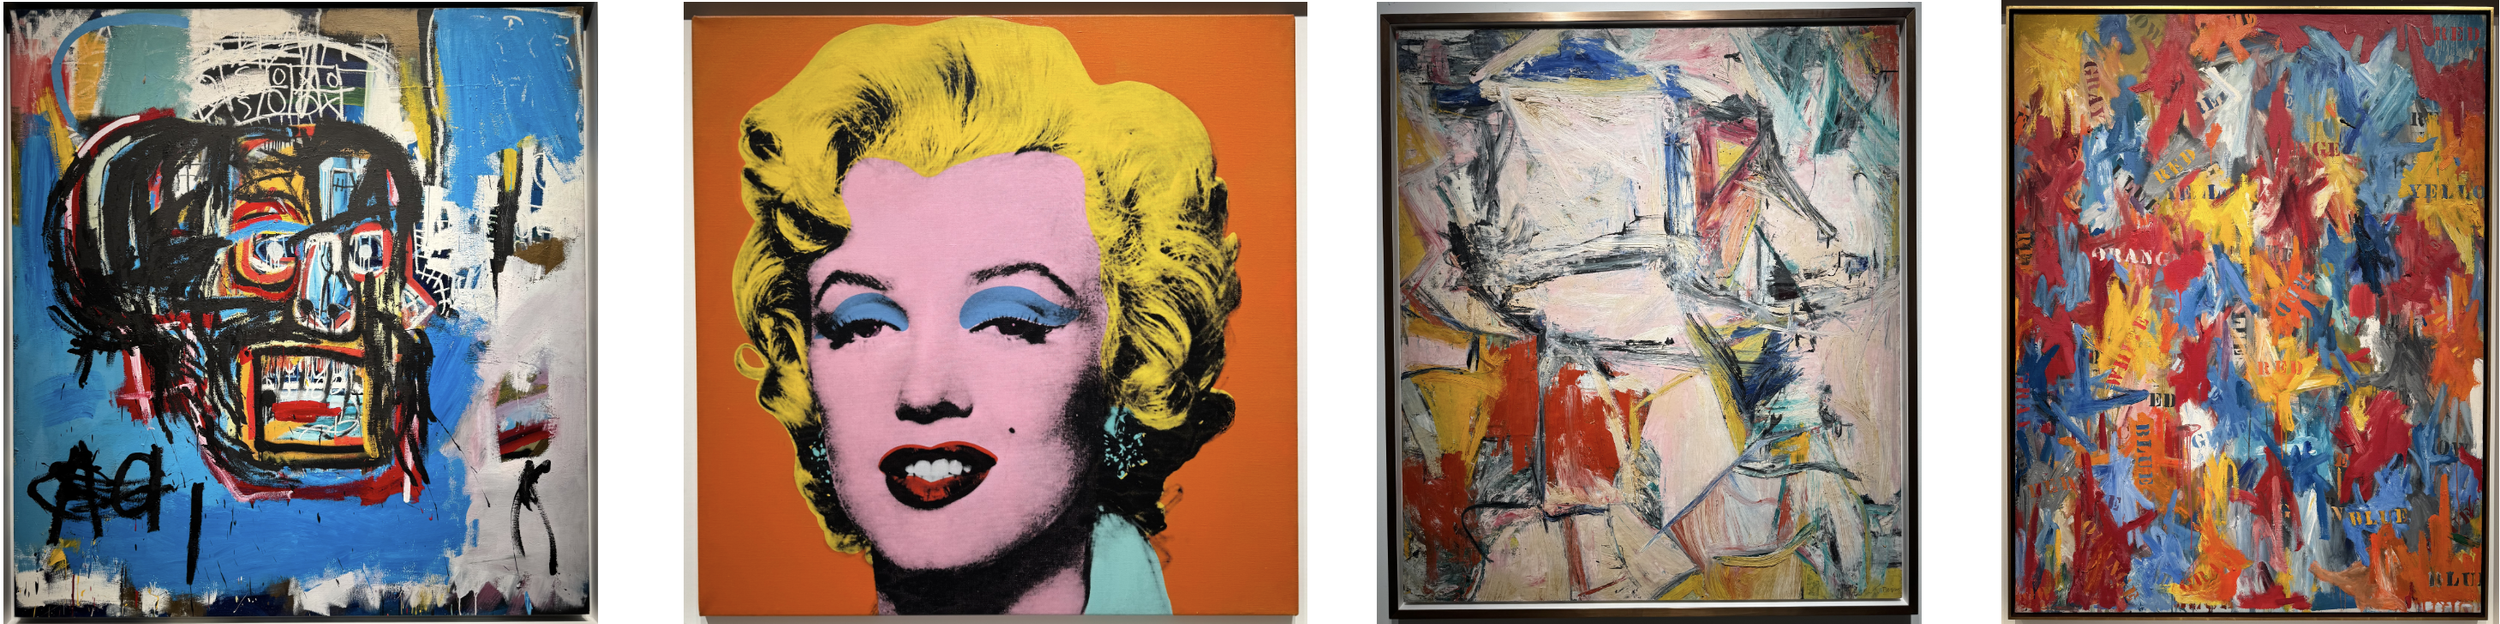
Sotheby's Icons exhibition, currently on view in New York, is intended as a mini compendium of key auction sales at the house over the decades. And yet, ironically, it is in large part a story about private sales -- and above all, those which brought four masterpieces to the collection of Citadel CEO and mega-collector Ken Griffin, notwithstanding silence in the exhibition wall text about the post-auction sales histories of these paintings.
The first is Basquiat's 1982 Untitled head, which sold to Yusaku Maezawa at Sotheby's in 2017 for $110.5 million, setting an all-time auction record for any American artist (surpassed at Christie’s in 2022 with the $195 million sale of Warhol’s 1964 Shot Sage Blue Marilyn). Maezawa’s $200 million private sale of this Basquiat to Griffin was reported in Artnet News in May 2024, but the story remained publicly uncorroborated until now.
The $200 million price attained for Shot Sage Blue Marilyn was in no small part benchmarked by another private Griffin purchase of a Warhol painting included in “Icons,” namely the closely related Shot Orange Marilyn (1964), originally purchased at Sotheby’s by S.I. Newhouse for $17.3 million in 1988 and much later, in 2017, sold to Griffin for approximately $200 million.
Also in Icons is De Kooning’s Interchange (1955), which sold at Sotheby’s for $20.7 million, but, market-wise, is perhaps best known for its 2015 private purchase by Griffin from music mogul David Geffen for a reported $300 million in a deal reported also to include the $200 million purchase of Pollock’s Number 17A (1948). The $300 million purchase of the De Kooning was the highest known price paid for a work of art in any market, and today, it is still second only to the Salvator Mundi by Leonardo da Vinci (and/or workshop), which fetched $450.3 million at Christie’s, NY in 2017.
The fourth significant Griffin loan to Icons is Jasper Johns’s False Start (1959), which sold for $17 million at Sotheby’s in 1988 and later, in 2006, was sold by Geffen to Griffin for a reported $80 million. It is worth considering what the painting might bring today, nearly 20 years later.
Irrespective of any possible such price growth, these four paintings comprise a total of approximately $780 million in total realized private sales, none of which is mentioned in the exhibition wall text. This is not a criticism; to the contrary, it was a pleasure and a rare opportunity to be able to see these major paintings, among others, assembled together for what may be the only time, but it’s also worth observing that the unspoken epicenter of this exhibition allegedly about auction sales, is indeed something quite apart than that.
Also not to miss in Icons are brilliant paintings by Kahlo, Klimt, Mondrian, Sargent, Still, and others, all looking their best in the Breuer building, itself a masterpiece.